Baba Metsia 66b en français · בבא מציעא ס״ו ב
Traduction française du daf 66b du traité Baba Metsia (Bava Metzia 66b en anglais), avec le texte araméen, l’anglais de Sefaria et le scan de la page, pour étudier le Daf Yomi.
Ouvrir dans le lecteur interactifLire le daf du jour
Traduction française de Baba Metsia 66b
Les traductions françaises de Daf Study sont générées par IA à partir de l’édition anglaise de Sefaria. Elles peuvent contenir des erreurs : vérifie toujours un passage avec le texte source.
Si tu le souhaites, dis plutôt que la Michna parle d’un cas où l’emprunteur a dit au prêteur : « Si je ne te rembourse pas dans les trois ans, tu acquerras le champ dès maintenant », et où ils ont accompli un acte formel d’acquisition. Puisqu’un acte d’acquisition a été accompli à ce moment-là, il s’agit d’une vente valable et non d’une asmakhta.
Mar Yanuka et Mar Kashisha, le fils cadet et le fils aîné de Rav Ḥisda, dirent à Rav Ashi : « Voici ce que disent les Sages de Neharde’a au nom de Rav Naḥman : concernant cette asmakhta décrite dans la Michna, elle produit une acquisition au moment prévu, mais pas en dehors de ce moment. »
Rav Ashi comprit qu’ils voulaient dire que le prêteur n’acquiert le champ qu’à l’échéance du prêt. Il leur dit : « Cette déclaration ne semble enseigner aucune règle nouvelle, car il en va de même pour toute chose : elle produit une acquisition au moment prévu, mais pas en dehors de ce moment. »
Rav Ashi suggère : « Peut-être vouliez-vous dire ceci : si l’emprunteur rencontre le prêteur avant l’échéance, c’est-à-dire avant que le remboursement du prêt ne soit dû, et lui demande d’acquérir le champ, le prêteur l’acquiert, car on présume que l’emprunteur est sincère. Mais si l’emprunteur rencontre le prêteur après l’échéance, c’est-à-dire au moment où le remboursement du prêt est dû, et lui demande d’acquérir le champ, le prêteur ne l’acquiert pas. Pourquoi ? L’emprunteur lui dit cela par honte de ne pas avoir remboursé sa dette, mais il n’avait pas réellement l’intention de lui faire acquérir le champ. »
La Guemara fait remarquer : Mais il n’en est pas ainsi, car la halakha est que le prêteur n’acquiert pas le champ, même si l’emprunteur a dit cela avant l’échéance. Et s’il lui a demandé de l’acquérir, c’est seulement parce qu’il pense : « Ainsi, lorsque l’échéance arrivera, il ne viendra pas me déranger. » Autrement dit, il cherche à gagner du temps jusqu’à ce qu’il puisse rembourser le prêt, mais il n’était pas sincère lorsqu’il a dit que le prêteur pouvait acquérir le champ.
Rav Pappa dit : concernant cette asmakhta, elle produit parfois une acquisition et parfois non. Comment cela ? Si le prêteur rencontre l’emprunteur alors que celui-ci boit de la bière, l’acquisition a lieu, car si l’emprunteur a accepté de transférer la propriété de son champ alors qu’il ne semblait pas être en difficulté financière — par exemple, alors qu’il savourait une boisson —, on présume qu’il l’a fait en acceptant pleinement les conséquences ; la transaction est donc valable. En revanche, si le prêteur rencontre l’emprunteur alors que celui-ci cherche de l’argent pour rembourser le prêt, son accord ne produit pas d’acquisition, car il est clair que l’emprunteur a fait cette déclaration sous la contrainte.
Rav Aḥa de Difti dit à Ravina : « Dans le cas où le prêteur a rencontré l’emprunteur alors que celui-ci buvait de la bière, peut-être buvait-il pour apaiser sa peur et se trouvait-il réellement sous pression financière. Ou peut-être quelqu’un d’autre lui avait-il promis de l’argent ; il reste donc dans une situation précaire, même s’il peut rembourser sa dette. Sa promesse ne serait alors, là encore, qu’une asmakhta. » Ravina dit plutôt qu’il existe une autre distinction : si l’emprunteur tient à obtenir le prix de son bien, c’est-à-dire s’il refuse de vendre ses biens à un prix inférieur à leur valeur marchande, le prêteur a certainement acquis le champ. En effet, l’emprunteur n’est manifestement pas dans une situation financière aussi précaire ; on présume donc qu’il a accepté de plein gré de donner le champ au prêteur.
Rav Aḥa de Difti dit à Ravina : « Même dans ce cas, peut-être l’emprunteur pense-t-il qu’il doit se montrer exigeant sur le prix de son bien afin que le prix de ses autres terres ne baisse pas. Si les gens savent qu’il a besoin d’argent, ils le pousseront à baisser le prix. Il se comporte donc comme s’il tenait à obtenir le prix demandé, alors qu’en réalité il ne souhaitait pas vendre le bien du tout. » Rav Pappa dit plutôt qu’il existe une autre distinction : si l’emprunteur tient à toute autre terre qu’il possède et refuse de la vendre, même à sa valeur marchande, il est évident qu’il ne connaît pas de difficultés financières ; dans ce cas, le créancier acquiert certainement le champ.
Et Rav Pappa dit : bien que les Sages aient dit qu’une asmakhta ne produit pas d’acquisition, de sorte que, même si l’emprunteur a stipulé que le prêteur pourrait recouvrer la dette en saisissant un terrain, le prêteur ne l’acquiert pas, ce terrain est néanmoins considéré comme réservé au prêteur à titre de garantie désignée [apoteiki], afin qu’il puisse s’y faire rembourser jusqu’à concurrence de la somme due.
Rav Huna, fils de Rav Natan, dit à Rav Pappa : « L’emprunteur a-t-il dit au prêteur : “Acquiers-le en vue du recouvrement de la dette” ? » Puisque l’emprunteur n’a pas précisé que le transfert de propriété du champ tenait lieu de remboursement de la dette, sa déclaration est considérée comme une asmakhta, et le champ n’est pas réservé comme garantie désignée. Mar Zutra, fils de Rav Mari, dit à Ravina : « Et s’il lui avait dit : “Acquiers-le en vue du recouvrement de la dette”, le prêteur l’aurait-il alors acquis ? Après tout, il s’agit d’une asmakhta, et la halakha est qu’une asmakhta ne produit pas d’acquisition. »
La Guemara pose une question : mais alors, à quelle garantie désignée Rav Pappa fait-il référence ? Selon l’analyse de Mar Zutra, cela ne change rien que l’emprunteur ait ou non dit que le terrain était réservé comme garantie désignée du prêt. La Guemara explique : Rav Pappa parle, par exemple, d’un cas où l’emprunteur a dit au prêteur : « Non seulement je te donnerai le terrain si je ne rembourse pas le prêt, mais même si je te rembourse, tu ne recevras le paiement que de ce terrain, car je m’acquitterai de ma dette envers toi en te donnant une partie de ce champ. » Dans ce cas, l’asmakhta est annulée, tandis que la promesse de remboursement au moyen du terrain demeure valable.
§ La Guemara rapporte : un homme vendit un terrain à un autre en lui accordant une garantie contre l’éviction, ce qui signifie que si les créanciers du vendeur saisissaient le terrain, le vendeur rembourserait à l’acheteur le prix d’achat. L’acheteur lui dit : « Si tes créanciers me saisissent le terrain, me laisseras-tu recouvrer ce qui m’est dû sur la meilleure partie de tes terres de première qualité ? » Le vendeur lui répondit : « Je ne te laisserai pas recouvrer sur la meilleure partie de mes terres de première qualité, car je veux la garder pour moi. Mais je te laisserai recouvrer sur les autres terres de première qualité que je possède. » Finalement, des créanciers saisirent le terrain de l’acheteur et, entre-temps, une inondation submergea la meilleure partie des terres de première qualité du vendeur.
Comme les terres de première qualité qui lui restaient étaient désormais les meilleures qu’il possédait, le vendeur refusa de les donner à l’acheteur et chercha à le rembourser avec des terres de qualité moyenne, conformément à la halakha habituelle concernant l’indemnisation d’un acheteur. Rav Pappa envisagea de dire : puisque le vendeur avait dit à l’acheteur qu’il pourrait recouvrer sur ses terres de première qualité, et que celles-ci étaient intactes, le vendeur devait les lui donner, conformément à sa promesse.
Rav Aḥa de Difti dit à Ravina : « Mais le vendeur pourrait dire à l’acheteur : “Quand je t’ai dit que je te laisserais recouvrer sur mes terres de première qualité, c’était lorsque la meilleure partie de ces terres était intacte. Mais maintenant, mes terres de première qualité tiennent lieu de ce qui était auparavant la meilleure partie de mes terres de première qualité ; je ne suis pas tenu de te donner ce qu’il y a de meilleur dans mes biens.” »
La Guemara rapporte : Rav bar Shabba devait de l’argent à Rav Kahana. Rav bar Shabba lui dit : « Si je ne te rembourse pas à telle date, tu pourras recouvrer la dette sur ce vin. » Rav Pappa envisagea de dire : lorsque nous avons dit qu’une asmakhta ne produit pas d’acquisition, cela ne s’applique qu’aux terres, qui ne sont pas destinées à être vendues, c’est-à-dire qui ne sont généralement pas achetées et vendues sur le marché. La promesse est donc invalide, car il n’avait pas réellement l’intention de les lui donner. Mais dans le cas du vin, puisqu’il est destiné à être vendu, il est considéré comme de l’argent ; le prêteur peut donc recouvrer la dette sur le vin, comme sur tout autre bien ayant une valeur monétaire.
Rav Huna, fils de Rav Yehoshua, dit à Rav Pappa : « Voici ce que nous disons au nom de Rabba : toute déclaration comportant une condition introduite par le mot “si” ne produit pas d’acquisition. Tout accord qui ne comporte pas d’engagement ferme, mais qui oblige une personne en cas de réalisation d’un événement particulier, a le statut d’une asmakhta et ne produit pas d’acquisition, car celui qui pose la condition n’avait pas réellement l’intention de tenir son engagement. »
§ Rav Naḥman dit : maintenant que les Sages ont dit qu’une asmakhta ne produit pas d’acquisition, dans un cas comme celui de la Michna, où quelqu’un a promis à un autre un terrain en remboursement d’une dette, si le prêteur l’a effectivement pris, il doit le rendre, ainsi que la valeur de tous les produits qu’il en a consommés. La Guemara pose une question : faut-il en conclure que Rav Naḥman considère qu’une renonciation au paiement faite par erreur n’est pas valable, autrement dit que si quelqu’un renonce par erreur au remboursement d’un prêt d’un montant donné, il peut revenir sur sa décision ? Dans ce cas, l’emprunteur pensait que le prêteur avait acquis le terrain et l’a donc laissé en consommer les produits.
Mais il a été rapporté que les amoraïm étaient en désaccord précisément sur cette question : si quelqu’un vend à un autre les fruits d’un palmier avant qu’ils ne mûrissent, Rav Huna dit qu’il peut revenir sur la vente et l’annuler tant que les fruits ne sont pas encore apparus, puisqu’ils n’existent pas encore. Mais une fois qu’ils sont apparus, même s’ils ne sont pas mûrs, il ne peut plus revenir sur la vente, car dès lors que les fruits faisant l’objet de l’acquisition existent, la vente a pris effet. Rav Naḥman dit, quant à lui, qu’il peut revenir sur la vente même après leur apparition, car on ne peut transférer la propriété d’une chose qui n’existe pas encore ; or, la transaction proprement dite a été conclue avant que les fruits n’existent.
Et Rav Naḥman dit : « Je reconnais que si l’acheteur a saisi les fruits et les a consommés, nous ne lui en réclamons pas la valeur. » En effet, puisque le vendeur avait initialement accepté la transaction, bien qu’elle reposât sur une erreur juridique, on peut supposer qu’il avait décidé de renoncer à ses droits sur les fruits et avait permis à l’autre de les prendre. On pourrait donc en conclure que Rav Naḥman considère qu’une renonciation faite par erreur est valable. La Guemara rejette cette preuve : là, il s’agit d’une vente, dans laquelle on peut dire que le vendeur a renoncé à ses droits sur les fruits. Ici, il s’agit d’un prêt, et ne pas obliger le prêteur à rembourser à l’emprunteur la valeur des produits consommés est considéré comme une forme d’intérêt.
Rava dit :
Texte source et traduction anglaise
בבא מציעא ס״ו ב · texte araméen et hébreu
אִיבָּעֵית אֵימָא: דַּאֲמַר לֵיהּ קְנִי מֵעַכְשָׁיו.
אֲמַרוּ לֵיהּ מָר יָנוֹקָא וּמָר קַשִּׁישָׁא בְּנֵי דְּרַב חִסְדָּא לְרַב אָשֵׁי, הָכִי אָמְרִי נְהַרְדְּעָאֵי מִשְּׁמֵיהּ דְּרַב נַחְמָן: הַאי אַסְמַכְתָּא, בְּזִמְנֵיהּ קָנְיָא, בְּלָא זִמְנֵיהּ לָא קָנְיָא.
אֲמַר לְהוּ: כֹּל מִידֵּי, בְּזִמְנֵיהּ קָנֵי, בְּלָא זִמְנֵיהּ לָא קָנֵי.
דִּלְמָא הָכִי קָאָמְרִיתוּ: אַשְׁכְּחֵיהּ בְּגוֹ זִמְנֵיהּ וַאֲמַר לֵיהּ קְנִי – קָנֵי, בָּתַר זִמְנֵיהּ וַאֲמַר לֵיהּ קְנִי – לָא קָנֵי. מַאי טַעְמָא – מֵחֲמַת כִּיסּוּפָא הוּא דְּקָאָמַר לֵיהּ.
וְלָא הִיא, דַּאֲפִילּוּ בְּגוֹ זִמְנֵיהּ נָמֵי לָא קָנֵי, וְהַאי דְּקָאָמַר לֵיהּ ״קְנִי״ – קָא סָבַר: כִּי מָטֵי זִמְנֵיהּ, לָא לַיְתֵי לִיטְרְדַן.
אָמַר רַב פָּפָּא: הַאי אַסְמַכְתָּא, זִימְנִין קָנְיָא וְזִימְנִין לָא קָנְיָא. אַשְׁכְּחֵיהּ דְּקָא שָׁתֵי שִׁכְרָא – קָנֵי. דְּקָא מְהַפֵּךְ אַזּוּזֵי – לָא קָנֵי.
אֲמַר לֵיהּ רַב אַחָא מִדִּפְתִּי לְרָבִינָא: דִּלְמָא לְפַכּוֹחֵי פַּחְדֵּיהּ קָא שָׁתֵי, אִי נָמֵי: אִינִישׁ אַחֲרִינָא אַסְמְכֵיהּ אַזּוּזֵי! אֶלָּא אָמַר רָבִינָא: אִי קָפֵיד בִּדְמֵי – וַדַּאי קָנֵי.
אֲמַר לֵיהּ רַב אַחָא מִדִּפְתִּי לְרָבִינָא: דִּלְמָא סָבַר כִּי הֵיכִי דְּלָא תִּיתְּזִיל אַרְעֵיהּ, אֶלָּא אָמַר רַב פָּפָּא: אִי קָפֵיד בְּאַרְעָא, וַדַּאי קָנֵי.
וְאָמַר רַב פָּפָּא: אַף עַל גַּב דַּאֲמוּר רַבָּנַן אַסְמַכְתָּא לָא קָנְיָא, אַפּוֹתֵיקֵי הָוְיָא לְמִיגְבֵּא מִינַּהּ.
אֲמַר לֵיהּ רַב הוּנָא בְּרֵיהּ דְּרַב נָתָן לְרַב פָּפָּא: מִי קָאָמַר לֵיהּ קְנִי לְגוּבְיָינָא? אֲמַר לֵיהּ מָר זוּטְרָא בְּרֵיהּ דְּרַב מָרִי לְרָבִינָא: וְאִי אָמַר קְנִי לְמִיגְבֵּא מִינֵּיהּ – קָנֵי? סוֹף סוֹף אַסְמַכְתָּא הִיא, וְאַסְמַכְתָּא לָא קָנְיָא.
אֶלָּא אַפּוֹתֵיקֵי דְּאָמַר רַב פָּפָּא, מַאי הִיא: דַּאֲמַר לֵיהּ לֹא יְהֵא לְךָ פֵּרָעוֹן אֶלָּא מִזּוֹ.
הָהוּא גַּבְרָא דְּזַבֵּין לֵיהּ אַרְעָא לְחַבְרֵיהּ בְּאַחְרָיוּת. אֲמַר לֵיהּ: אִי טָרְפוּ לַיהּ מִנַּאי מַגְבֵּית לִי מֵעִידֵּי עִידִּית דְּאִית לָךְ. אֲמַר לֵיהּ: מֵעִידֵּי עִידִּית לָא מַגְבֵּינָא לָךְ, דְּבָעֵינָא לְמֵיקַם קַמַּאי, אֶלָּא מַגְבֵּינָא לָךְ מֵעִידִּית אַחֲרִיתִ[י] דְּאִית לִי. לְסוֹף טַרְפוּהָ מִינֵּיהּ, אֲתָא בִּדְקָא שְׁקֵיל לְעִידֵּי עִידִּית.
סְבַר רַב פָּפָּא לְמֵימַר: מֵעִידִּית אֲמַר לֵיהּ, וְהָא קָיְימָא.
אֲמַר לֵיהּ רַב אַחָא מִדִּפְתִּי לְרָבִינָא: וְלֵימָא לֵיהּ, כִּי אֲמַרִי לָךְ אֲנָא מַגְבֵּינָא לָךְ – דַּהֲוָה עִידֵּי עִידִּית קָיְימָא, הַשְׁתָּא קָיְימָא לֵיהּ עִידִּית בִּמְקוֹם עִידֵּי עִידִּית.
רַב בַּר שְׁבָא הֲוָה מַסֵּיק בֵּיהּ רַב כָּהֲנָא זוּזֵי. אֲמַר לֵיהּ: אִי לָא פָּרַעְנָא לָךְ לְיוֹם פְּלוֹנִי – גְּבִי מֵהַאי חַמְרָא. סְבַר רַב פָּפָּא לְמֵימַר: כִּי אָמְרִינַן אַסְמַכְתָּא לָא קָנְיָא – הָנֵי מִילֵּי בְּאַרְעָא, דְּלָאו לְזַבּוֹנֵי קָיְימָא. אֲבָל חַמְרָא כֵּיוָן דִּלְזַבּוֹנֵי קָאֵי – כְּזוּזֵי דָּמֵי.
אֲמַר לֵיהּ רַב הוּנָא בְּרֵיהּ דְּרַב יְהוֹשֻׁעַ לְרַב פָּפָּא, הָכִי אָמְרִינַן מִשְּׁמֵיהּ דְּרַבָּה: כֹּל דְּאִי – לָא קָנֵי.
אָמַר רַב נַחְמָן: הַשְׁתָּא דַּאֲמוּר רַבָּנַן אַסְמַכְתָּא לָא קָנְיָא, הָדְרָא אַרְעָא וְהָדְרִי פֵּירֵי. לְמֵימְרָא דְּסָבַר רַב נַחְמָן מְחִילָה בְּטָעוּת לָא הָוְיָא מְחִילָה?
וְהָאִיתְּמַר: הַמּוֹכֵר פֵּירוֹת דֶּקֶל לַחֲבֵירוֹ. אָמַר רַב הוּנָא: עַד שֶׁלֹּא בָּאוּ לָעוֹלָם – יָכוֹל לַחְזוֹר בּוֹ. מִשֶּׁבָּאוּ לָעוֹלָם – אֵין יָכוֹל לַחְזוֹר בּוֹ. וְרַב נַחְמָן אָמַר: אַף מִשֶּׁבָּאוּ לָעוֹלָם יָכוֹל לַחְזוֹר בּוֹ,
וְאָמַר רַב נַחְמָן: מוֹדֵינָא דְּאִי שָׁמֵיט וְאָכֵיל – לָא מַפְּקִינַן מִינֵּיהּ! הָתָם זְבִינֵי, הָכָא הַלְוָאָה.
אָמַר רָבָא:
Bava Metzia 66b · traduction anglaise de Sefaria
If you wish, say instead that the mishna is referring to a case where the borrower said to the lender: If I do not repay you within three years, you will acquire the field from now, and they performed a formal act of acquisition. Since an act of acquisition was performed at the time, this is a proper sale and not an asmakhta.
Mar Yanuka and Mar Kashisha, the younger and elder sons of Rav Ḥisda, said to Rav Ashi: This is what the Sages of Neharde’a say in the name of Rav Naḥman: With regard to this asmakhta described in the mishna, it effects acquisition at its proper time, but it does not effect acquisition not at its proper time.
Rav Ashi understood them to be saying that the lender acquires the field only when the loan is due, and he said to them: This statement seems to teach no novel ruling, as the same is true of every matter: It effects acquisition at its proper time, but it does not effect acquisition not at its proper time.
Rav Ashi suggests: Perhaps you meant to say this: If the borrower encountered the lender within its time, i.e., before the payment of the loan was due, and told him to acquire the field, the lender acquires the field, as it is assumed that the borrower was sincere. But if the borrower encountered the lender after its time, i.e., when the payment of the loan was due, and told the lender to acquire the field, he does not acquire it. What is the reason for this? The borrower says this to the lender out of shame with regard to his failure to pay the debt, but he did not really intend for him to acquire the field.
The Gemara comments: But this is not so, as the halakha is that the lender does not acquire the field even if the borrower stated this within its time. And as for the fact that the borrower told him to acquire it, he told him this only because he thinks: This will ensure that when the time for payment arrives, he will not come and disturb me. In other words, he is trying to buy time until he can repay the loan, but he was not sincere in his statement that the lender may acquire the field.
Rav Pappa says: With regard to this asmakhta, sometimes it effects acquisition and sometimes it does not effect acquisition. How so? If the lender encountered the borrower while the borrower was drinking beer, it effects acquisition, as, if the borrower agreed to transfer ownership of his field when he did not appear to be in financial stress, such as when he was enjoying a drink, he assumedly did so with full acceptance of the consequences, and therefore the transaction is valid. By contrast, if the lender encountered the borrower when he was searching for money with which to repay the loan, his agreement does not effect acquisition, as it is clear the borrower made the statement under duress.
Rav Aḥa of Difti said to Ravina: In the case where the lender encountered the borrower while he was drinking beer, perhaps he was drinking to neutralize his fear, and he really was under financial pressure. Or, perhaps someone else promised him money, and therefore he remains in a precarious position even though he can repay the debt, which would again mean that his promise is merely an asmakhta. Rather, Ravina said that there is a different distinction: If the borrower is particular about the money, i.e., if he is unwilling to sell his property at less than its market value, the lender has certainly acquired the field, as the borrower is clearly not in such a precarious financial position, and he is therefore assumed to have willingly stated his agreement to give the field to the lender.
Rav Aḥa of Difti said to Ravina: Even in that case, perhaps the borrower thinks that he ought to present himself as particular about the price of his property in order that the price of his other lands not be lowered. If people know that he is in need of money they will pressure to him to lower the price, and therefore he acts as though he is particular about the price, but in reality he did not wish to sell the property at all. Rather, Rav Pappa said that there is a different distinction: If he is particular about any other land he owns and does not want to sell it even at its market rate, he is clearly not suffering from financial problems, and in that case the creditor certainly acquires the field.
And Rav Pappa said: Even though the Sages said that an asmakhta does not effect acquisition, and therefore even if he stipulated that the lender can collect the debt by seizing land, the lender does not acquire that land, nevertheless, the land is considered to be set aside as designated repayment [apoteiki] for the lender to collect repayment from it up to the amount of money owed.
Rav Huna, son of Rav Natan, said to Rav Pappa: Did the borrower say to the lender: Acquire it for the sake of debt collection? Since the borrower did not specify that transferring ownership of the field was in place of the payment of the debt, his statement is considered an asmakhta, and the field is not set aside as designated repayment. Mar Zutra, son of Rav Mari, said to Ravina: And if he had said to him: Acquire it for the sake of debt collection, would the lender then acquire it? Ultimately, it is an asmakhta, and the halakha is that an asmakhta does not effect acquisition.
The Gemara poses a question: But in that case, what is the designated repayment spoken of by Rav Pappa? According to Mar Zutra’s analysis, it makes no difference whether or not he said it was set aside as designated repayment of the loan. The Gemara explains: Rav Pappa is referring to a case, for example, where the borrower said to the lender: Not only will I give you the land if I fail to repay the loan, but even if I do pay you will receive payment only from this land alone, as I will pay off my debt to you by giving you land from this field. In that case the asmakhta is negated, while the promise of repayment from the land remains intact.
§ The Gemara relates: There was a certain man who sold land to another with a property guarantee, meaning that in the event that land is seized by the seller’s creditors, the seller will reimburse the buyer his purchase money. The buyer said to him: If your creditors seize the land from me, will you allow me to collect that which is owed to me from the most superior quality of the superior-quality land that you have? The seller said to him: I will not allow you to collect from the most superior quality of my superior-quality land, as I want to keep those before me. But I will allow you to collect from other superior-quality land I have. Ultimately, creditors seized the field from the buyer, and in the meantime a flood came and flooded the seller’s most superior quality of his superior-quality land.
As his remaining superior-quality land was now the best he had, the seller was unwilling to give them to the buyer and sought to repay him with intermediate-quality land, in accordance with the standard halakha concerning reimbursement to a buyer. Rav Pappa thought to say: Since the seller said to the buyer that he could collect from his superior-quality land, and this superior-quality land is intact, the seller must give it to him, in accordance with his promise.
Rav Aḥa of Difti said to Ravina: But let the seller say to the buyer: When I said to you that I would allow you to collect from my superior-quality land, that was when the most superior quality of my superior-quality land was intact. But now my superior-quality land stands for me in place of the most superior quality of the superior-quality land I had before, and I am not obligated to give you the very best of my property.
The Gemara relates: Rav bar Shabba owed money to Rav Kahana. Rav bar Shabba said to him: If I do not repay you by such and such a date, you can collect the debt from this wine. Rav Pappa thought to say: When we said that an asmakhta does not effect acquisition, this matter applies only to land, which does not stand to be sold, i.e., which is not typically bought and sold on the market, and therefore the promise is invalid, as he did not genuinely intend to give it to him. But in the case of wine, since it does stand to be sold, it is considered like money, and therefore he can claim the debt from wine, as he can claim the debt from any other item with monetary worth.
Rav Huna, son of Rav Yehoshua, said to Rav Pappa: This is what we say in the name of Rabba: Any statement including a condition introduced with the word: If, does not effect acquistion. Any agreement that does not involve a definitive commitment but does obligate one in the event of a particular outcome has the status of an asmakhta and does not effect acquisition, as the one setting the condition did not really intend to fulfill the commitment.
§ Rav Naḥman said: Now that the Sages have said that an asmakhta does not effect acquisition, in a case such as that in the mishna, when one promised another land for the repayment of a debt, if the lender in fact took it, the land must be returned and the value of any produce the creditor consumed from this land must also be returned. The Gemara poses a question: Is this to say that Rav Naḥman maintains that mistaken forgiveness of payment is not valid forgiveness, meaning that if one forgoes repayment of a loan of a certain amount of money in error, he can change his mind? In this case, the borrower had thought that the lender had acquired the land, and he therefore allowed him to consume the produce.
But it was stated that amora’im disputed this very issue: If one sells the fruit of a palm tree to another before the fruit ripens, Rav Huna says: He can retract and cancel the sale until the fruits have come into the world, as the fruit is not yet in existence. But once they have come into the world, even if they are still unripe, he cannot retract, as once the fruits that are being acquired exist, the sale has gone into effect. And Rav Naḥman says: He can retract even once they have come into the world, as one cannot transfer ownership of an entity that has not yet come into the world, and the actual transaction was performed before the fruits existed.
And Rav Naḥman said: I concede that if the buyer seized the fruit and consumed it, we do not take its value from him. The reason is that since the seller initially accepted the transaction, although it involved a legal error, it can be assumed that he decided to waive his rights to the fruit and allowed the other to take it. Consequently, it can be demonstrated that Rav Naḥman holds that mistaken forgiveness is forgiveness. The Gemara rejects this proof: There, the discussion involves a sale, with regard to which it can be said that the seller waived his rights to the fruit. Here, it is referring to a loan, and not requiring the lender to reimburse the borrower for the produce consumed is considered a form of interest.
Rava said:
Texte de Sefaria : William Davidson Edition - Vocalized Aramaic (CC BY NC) ; William Davidson Edition - English (CC BY NC).
Scan de Baba Metsia 66b
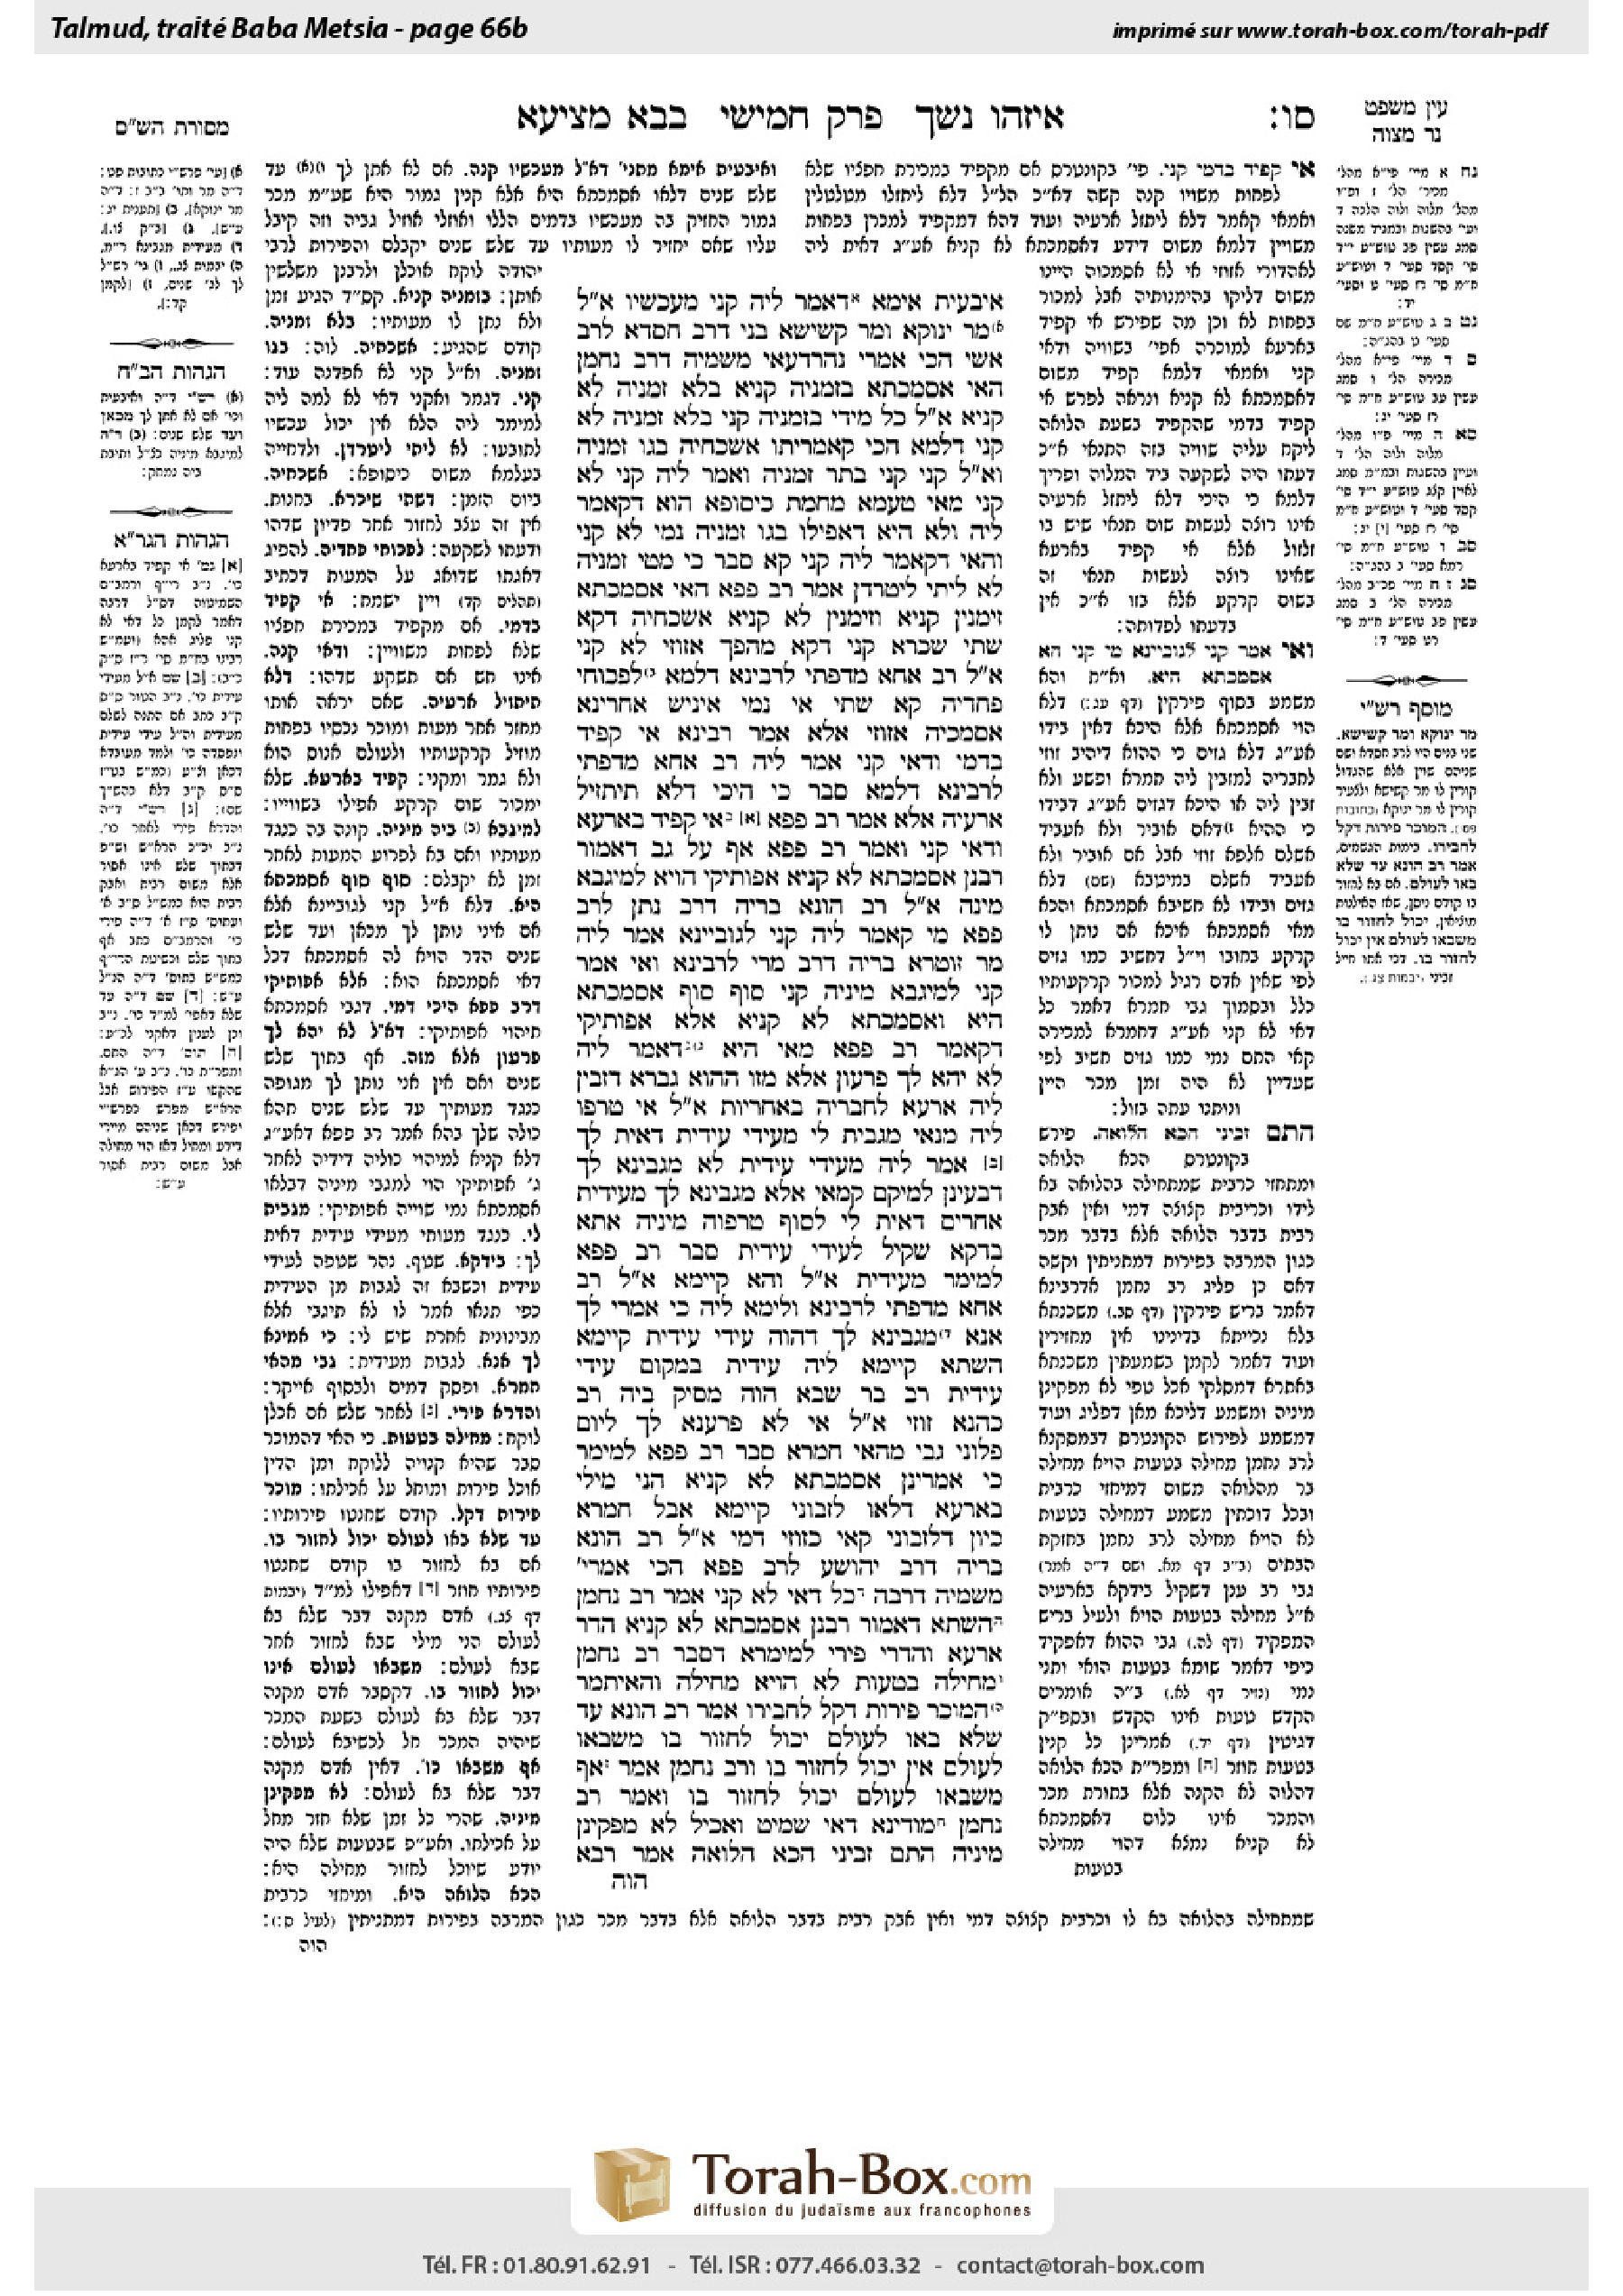
Scan : Torah-Box. Daf Study est un projet indépendant, sans affiliation ni approbation de Torah-Box ou de Sefaria.