Baba Metsia 68a en français · בבא מציעא ס״ח א
Traduction française du daf 68a du traité Baba Metsia (Bava Metzia 68a en anglais), avec le texte araméen, l’anglais de Sefaria et le scan de la page, pour étudier le Daf Yomi.
Ouvrir dans le lecteur interactifLire le daf du jour
Traduction française de Baba Metsia 68a
Les traductions françaises de Daf Study sont générées par IA à partir de l’édition anglaise de Sefaria. Elles peuvent contenir des erreurs : vérifie toujours un passage avec le texte source.
qu’il le rachète à raison de quatre dinars par an, alors même que les produits valent davantage ? Ici aussi, il n’en va pas autrement. Puisqu’il a fixé une déduction d’un montant déterminé qu’il n’est pas certain de percevoir, la pratique est permise, même s’il réalise effectivement un bénéfice grâce à cet arrangement.
Et celui qui interdit cet arrangement aurait pu te répondre que la halakha concernant un champ ancestral traite d’un bien consacré, pour lequel le Miséricordieux a institué une procédure de rachat, sur la base de laquelle les Sages ont déterminé le montant intégral du rachat. Ici, en revanche, il s’agit d’un prêt, qui a donc l’apparence d’un prêt à intérêt.
Rav Ashi a dit : Les anciens de la ville de Mata Meḥasya m’ont dit : une hypothèque non spécifiée [mashkanta] dure un an. La Guemara demande : Quelle conséquence pratique découle de cette règle ? La Guemara explique : cela signifie que si le prêteur en a consommé les produits pendant un an, l’emprunteur peut alors le déposséder ; sinon, l’emprunteur ne peut pas encore le déposséder, car une hypothèque non spécifiée ne dure pas moins longtemps.
Et Rav Ashi a dit : Les anciens de Mata Meḥasya m’ont dit : que signifie le mot mashkanta ? Il fait référence au fait que le champ réside [shekhuna] chez lui. La Guemara demande à nouveau : quelle conséquence pratique découle de cette déclaration ? La Guemara répond : cela concerne la halakha de celui dont le champ jouxte celui de son voisin. Puisque le champ hypothéqué réside chez lui, il est considéré dans une certaine mesure comme son bien ; il bénéficie donc du droit d’acheter un champ voisin avant qu’un tiers ne le fasse.
Rava a dit : La halakha ne suit ni ceux qui approuvent l’accord d’intérêt tacite de Rav Pappa, ni ceux qui approuvent les documents de Meḥoza, ni ceux qui approuvent les contrats de location de Neresh.
La Guemara précise ces déclarations : « La halakha ne suit pas ceux qui approuvent l’accord d’intérêt tacite de Rav Pappa » fait référence à cet accord de Rav Pappa (65a). Rav Pappa vendait de l’alcool et acceptait un paiement différé à un prix plus élevé, estimant cette pratique permise puisqu’il ne tirait aucun avantage de l’arrangement.
Que sont les documents de Meḥoza ? À Meḥoza, on prêtait de l’argent à quelqu’un pour qu’il l’investisse dans une entreprise commune, puis on ajoutait les bénéfices au principal, comme si l’opération était déjà conclue, et l’on inscrivait dans le document la somme totale due, y compris la part des bénéfices revenant au prêteur. Pourquoi est-il interdit d’agir ainsi ? Qui peut garantir qu’il y aura des bénéfices ? Il se peut que l’emprunteur subisse une perte ou gagne moins que prévu ; s’il paie finalement la somme intégrale inscrite dans le document, il versera alors un intérêt.
Mar, fils d’Ameimar, dit à Rav Ashi : « Père procédait ainsi, c’est-à-dire qu’il ajoutait les bénéfices au montant du contrat de prêt. Lorsque les emprunteurs venaient le voir et lui disaient qu’ils n’avaient pas réalisé suffisamment de bénéfices, il les croyait et réduisait la dette au montant qu’ils avaient effectivement gagné. » Rav Ashi lui dit : « Cela fonctionne tant que le prêteur est encore en vie ; mais s’il meurt et que le document se retrouve entre les mains des orphelins, qu’adviendra-t-il ? Ne sachant pas que les bénéfices ont été ajoutés au document, les orphelins réclameront la somme entière, ce qui constituera un intérêt. » La Guemara commente que cette remarque anodine de Rav Ashi fut « comme une erreur qui procède d’un gouvernant » (Ecclésiaste 10:5), et qu’Ameimar mourut peu après.
La Guemara examine la dernière règle. Que sont les contrats de location de Neresh ? Dans la ville de Neresh, on rédigeait un document ainsi : « Untel a hypothéqué son champ à untel. » L’emprunteur allait ensuite louer le champ à nouveau au prêteur, moyennant un loyer ajouté au remboursement du prêt. Cette transaction pose problème. À quel moment le prêteur en a-t-il acquis la propriété, pour pouvoir ensuite la céder à nouveau à l’emprunteur ? Puisqu’il n’est pas le véritable propriétaire du champ, le loyer constitue en réalité un paiement pour le délai de remboursement du prêt ; cet arrangement est donc considéré comme un prêt à intérêt.
La Guemara fait remarquer : De nos jours, lorsqu’on rédige un document ainsi : « Nous avons acquis le bien auprès de lui, puis nous avons attendu quelque temps, et l’emprunteur est ensuite allé le louer à nouveau pour tel prix », cette formule indique que le prêteur a acquis le champ et peut désormais le louer à d’autres. Elle est utilisée afin de ne pas fermer la porte aux emprunteurs potentiels et est permise, car l’opération n’a pas l’apparence d’un prêt à intérêt. La Guemara conclut : Mais cela n’est pas exact, car même si le champ est en sa possession, puisqu’il ne l’a pas acquis comme il se doit, l’opération est considérée comme un prêt à intérêt.
Michna : On ne peut pas conclure avec un commerçant un accord prévoyant un partage par moitié des bénéfices. Il est interdit de fournir des produits à un commerçant pour qu’il les vende dans sa boutique, la moitié des bénéfices revenant au prêteur. Dans un tel arrangement, le commerçant assume lui-même la moitié des pertes éventuelles de l’entreprise, ce qui revient à lui prêter la moitié des produits. Le prêteur reste responsable de l’autre moitié des pertes, et le commerçant fournit un service en vendant les produits pour lui. Si ce service est fourni gratuitement, il est considéré comme un intérêt versé au titre du prêt et est donc interdit. De même, on ne peut pas donner de l’argent à un commerçant pour qu’il achète des produits et les vende en partageant les bénéfices par moitié. Ces deux pratiques sont interdites, à moins que le propriétaire ne verse au commerçant un salaire pour son travail de vente ; ils peuvent alors se partager les bénéfices restants.
On ne peut pas donner des œufs à quelqu’un pour qu’il y fasse couver des poules en échange de la moitié des bénéfices, et on ne peut pas confier à quelqu’un des veaux ou des poulains, après en avoir évalué la valeur, afin qu’il les élève en échange de la moitié des bénéfices. Ces deux pratiques sont interdites, à moins que le propriétaire ne rémunère l’autre pour son travail et ne lui rembourse le coût de la nourriture qu’il donne aux animaux temporairement confiés à ses soins. Tout cela s’applique lorsque le prêteur fixe un bénéfice minimal garanti qu’il exige de recevoir, quelles que soient les circonstances touchant les animaux.
Mais on peut prendre des veaux ou des poulains à élever dans le cadre d’une entreprise commune, les bénéfices étant partagés par moitié : l’une des parties fournit les animaux et assume l’entière responsabilité des pertes, tandis que l’autre fournit le travail et la nourriture. Celui qui les élève peut les garder jusqu’à ce qu’ils atteignent le tiers de leur maturité ; ils sont alors vendus et les bénéfices partagés. Quant à un âne, il peut être élevé de cette manière jusqu’à ce qu’il soit assez grand pour porter une charge.
Guemara : Les Sages ont enseigné : Lorsque la Michna dit que le propriétaire doit rémunérer le gérant de l’entreprise comme un salarié, cela signifie qu’il doit le payer comme un salarié inactif. La Guemara demande : que signifie payer quelqu’un comme un salarié inactif ?
Texte source et traduction anglaise
בבא מציעא ס״ח א · texte araméen et hébreu
קָא פָרֵיק לַהּ בְּאַרְבְּעָה זוּזֵי, הָכָא נָמֵי לָא שְׁנָא.
וּמַאן דְּאָסַר – אָמַר לָךְ: שְׂדֵה אֲחוּזָּה הֶקְדֵּשׁ הִיא, וְרַחֲמָנָא אוֹקְמֵיהּ אַפִּדְיוֹן. הָכָא – הַלְוָאָה הִיא וּמִיחֲזֵי כְּרִבִּית.
אָמַר רַב אָשֵׁי: אֲמַרוּ לִי סָבֵי דְּמָתָא מַחְסֵיָא: סְתַם מַשְׁכַּנְתָּא – שַׁתָּא. לְמַאי נָפְקָא מִינַּהּ? דְּאִי אָכֵיל לַהּ שַׁתָּא – מָצֵי מְסַלֵּק לֵיהּ, וְאִי לָא – לָא מָצֵי מְסַלֵּק לֵיהּ.
וְאָמַר רַב אָשֵׁי: אֲמַרוּ לִי סָבֵי דְּמָתָא מַחְסֵיָא, מַאי ״מַשְׁכַּנְתָּא״ – דִּשְׁכוּנָה גַּבֵּיהּ. לְמַאי נָפְקָא מִינַּהּ? לְדִינָא דְּבַר מִצְרָא.
אָמַר רָבָא: לֵית הִלְכְתָא לָא כְּטַרְשֵׁי פַּפּוּנָאֵי, וְלָא כִּשְׁטָרֵי מָחוֹזְנָאֵי, וְלָא כַּחֲכִירֵי נַרְשָׁאֵי.
כְּטַרְשֵׁי פַּפּוּנָאֵי – כְּטַרְשֵׁי דְּרַב פָּפָּא.
שְׁטָרֵי מָחוֹזְנָאֵי – דְּזָקְפִי לֵיהּ לְרַוְוחָא אַקַּרְנָא, וְכָתְבִי לֵיהּ בִּשְׁטָרָא. מִי יֵימַר דְּהָוֵה רַוְוחָא?
אֲמַר לֵיהּ מָר בַּר אַמֵּימָר לְרַב אָשֵׁי: אַבָּא עָבֵיד הָכִי, וְכִי אָתוּ לְקַמֵּיהּ מְהֵימַן לְהוּ. אֲמַר לֵיהּ: תִּינַח הֵיכָא דְּאִיתֵיהּ לְדִידֵיהּ, אִי שָׁכֵיב וְנָפֵל שְׁטָרָא קַמֵּי יַתְמֵי, מַאי? הָוֵי ״כִּשְׁגָגָה שֶׁיֹּצָא מִלִּפְנֵי הַשַּׁלִּיט״ וְנָח נַפְשֵׁיהּ דְּאַמֵּימָר.
חֲכִירֵי נַרְשָׁאֵי, דְּכָתְבִי הָכִי: מִשְׁכֵּן לֵיהּ פְּלָנְיָא אַרְעֵיהּ לִפְלָנְיָא, וַהֲדַר חַכְרַהּ מִינֵּיהּ. אֵימַת קְנָאָהּ דְּאַקְנְיַיהּ נִהֲלֵיהּ?
וְהָאִידָּנָא דְּקָא כָתְבִי הָכִי: ״קְנֵינָא מִינֵּיהּ וּשְׁהֵינָא כַּמָּה עִידָּנֵי, וַהֲדַר חַכְרַהּ״, כְּדֵי שֶׁלֹּא תִּנְעוֹל דֶּלֶת בִּפְנֵי לוֹוִין – שַׁפִּיר דָּמֵי. וְלָאו מִלְּתָא הִיא.
מַתְנִי׳ אֵין מוֹשִׁיבִין חֶנְוָנִי לְמַחֲצִית שָׂכָר, וְלֹא יִתֵּן מָעוֹת לִיקַּח בָּהֶן פֵּירוֹת לְמַחֲצִית שָׂכָר, אֶלָּא אִם כֵּן נוֹתֵן לוֹ שְׂכָרוֹ כְּפוֹעֵל.
אֵין מוֹשִׁיבִין תַּרְנְגוֹלִין לְמֶחֱצָה, וְאֵין שָׁמִין עֲגָלִין וּסְיָיחִין לְמֶחֱצָה, אֶלָּא אִם כֵּן נוֹתֵן לוֹ שְׂכַר עֲמָלוֹ וּמְזוֹנוֹ.
אֲבָל מְקַבְּלִין עֲגָלִין וּסְיָיחִין לְמֶחֱצָה, וּמְגַדְּלִין אוֹתָן עַד שֶׁיְּהוּ מְשׁוּלָּשִׁין. וַחֲמוֹר עַד שֶׁתְּהֵא טוֹעֶנֶת.
גְּמָ׳ תָּנָא: כְּפוֹעֵל בָּטֵל. מַאי כְּפוֹעֵל בָּטֵל?
Bava Metzia 68a · traduction anglaise de Sefaria
that he redeems it at four dinars a year, despite the fact that the produce is worth more? Here too, it is no different. Since he established the deduction of a fixed sum that he cannot be sure he will receive, the practice is permitted, even if he in fact profits from the arrangement.
And the one who prohibits this arrangement could have said to you that the halakha with regard to an ancestral field is discussing consecrated property and the Merciful One established redemption for it, on the basis of which the Sages determined the full redemption. Here, by contrast, it is a loan, and therefore it has the appearance of interest.
Rav Ashi said: The elders of the town of Mata Meḥasya told me: An unspecified mortgage [mashkanta] is for a year. The Gemara poses a question: What is the practical difference resulting from this ruling? The Gemara explains: It means that if the lender consumed its produce for a year, the borrower can then remove him; but if not, the borrower cannot yet remove him, as an unspecified mortgage does not last less than this period of time.
And Rav Ashi said: The elders of Mata Meḥasya told me: What is the meaning of the word mashkanta? It is referring to the fact that it resides [shekhuna] with him. The Gemara again asks: What is the practical difference resulting from his statement? The Gemara answers: It is relevant for the halakha of one whose field borders the field of his neighbor. Since the mortgaged field resides with him, it is considered his property to a certain extent, and therefore he is granted the right to purchase a neighboring field before an outside party does so.
Rava said: The halakha is not in accordance with those who approve of the tacit interest agreement of Rav Pappa, nor in accordance with those who approve of the documents of Meḥoza, nor in accordance with those who approve of the tenancies of Neresh.
The Gemara clarifies these statements: The halakha is not in accordance with those who approve of the tacit interest agreement of Rav Pappa; this is referring to the tacit interest agreement of Rav Pappa (65a). Rav Pappa would sell liquor and accept delayed payment at a higher price, and believed this to be permitted since he did not gain anything from the arrangement.
What are the documents of Meḥoza? In Meḥoza they would lend money to someone for him to use in a joint business venture, and add the profits to the principal, as though the transaction were already completed, and they would write the full sum owed, including the lender’s share of the profits, in the document. The reason it is prohibited to do this is that who says there will be any profit? It is possible that the borrower will suffer a loss or earn less than expected, and he will eventually be paying interest if he pays the full amount recorded in the document.
Mar, son of Ameimar, said to Rav Ashi: Father would do so, i.e., he would add the profits to the sum of the loan contract, and when they came before him and told him they had not earned enough profit he would believe them and reduce the debt to the amount they had actually earned. Rav Ashi said to him: This works out well while the lender is still here, but if he dies and the document comes before the orphans, what would happen in that case? Unaware that profits have been added to the document, the orphans would demand the entire sum, which would constitute interest. The Gemara comments: This innocent observation of Rav Ashi’s was “like an error that proceeds from a ruler” (Ecclesiastes 10:5), and Ameimar died shortly afterward.
The Gemara addresses the final ruling. What are the tenancies of Neresh? In the town of Neresh they would write a document in this manner: So-and-so has mortgaged his land to so-and-so, and the borrower then went and leased it back from him for a fee that was added to the payment of the loan. This transaction is problematic. When did the lender acquire it, such that he can subsequently transfer it back to the borrower? As he is not the actual owner of the field, the money for the lease is actually payment for the delay in repaying the loan, and therefore this arrangement is considered interest.
The Gemara comments: And nowadays, when we write a document in this manner: We acquired the property from him and we waited a while and then the borrower went and leased it back for such and such a price, a formula that states that the lender has acquired the field and may now lease it to others, which is utilized so as not to lock the door in the face of potential borrowers, it is permitted, as it does not have the appearance of a loan with interest. The Gemara concludes: But this is not correct, as even if the field is in his possession, since he has not acquired it properly, it is considered interest.
MISHNA: One may not establish a deal with a storekeeper for half the profits. It is prohibited for one to provide a storekeeper with produce for him to sell in his store, with half the profits going to the lender. In such an arrangement, the storekeeper himself is responsible for half of any loss from the venture, effectively rendering half of the produce as a loan to the storekeeper. The lender remains responsible for the other half of any loss, and the storekeeper provides a service by selling his produce for him. This service, if provided free of charge, is viewed as interest paid for the loan, and is prohibited. And similarly, one may not give a storekeeper money with which to acquire produce for the storekeeper to sell for half the profits. These activities are both prohibited unless the owner gives the storekeeper his wages as a salaried laborer hired to sell the produce, after which they can divide the remaining profits.
One may not give eggs to another to place chickens on them in exchange for half the profits, and one may not appraise calves or foals for another to raise them for half the profits. These activities are both prohibited unless the owner gives the other wages for his toil and the cost of the food he gives to the animals in his temporary care. All this applies when the lender establishes a fixed minimum profit he insists on receiving regardless of what happens to the animals.
But one may accept calves or foals to raise as a joint venture for half of the earnings, with one side providing the animals and taking full responsibility for losses, and the other providing the work and the sustenance, and the one raising them may raise them until they reach one-third of their maturation, at which point they are sold and the profits shared. And with regard to a donkey, it can be raised in this manner until it is large enough to bear a load.
GEMARA: The Sages taught: When the mishna states that the owner must pay the manager of the venture as a salaried laborer, it means he must pay him as an idle laborer. The Gemara poses a question: What does it mean to pay someone as an idle laborer?
Texte de Sefaria : William Davidson Edition - Vocalized Aramaic (CC BY NC) ; William Davidson Edition - English (CC BY NC).
Scan de Baba Metsia 68a
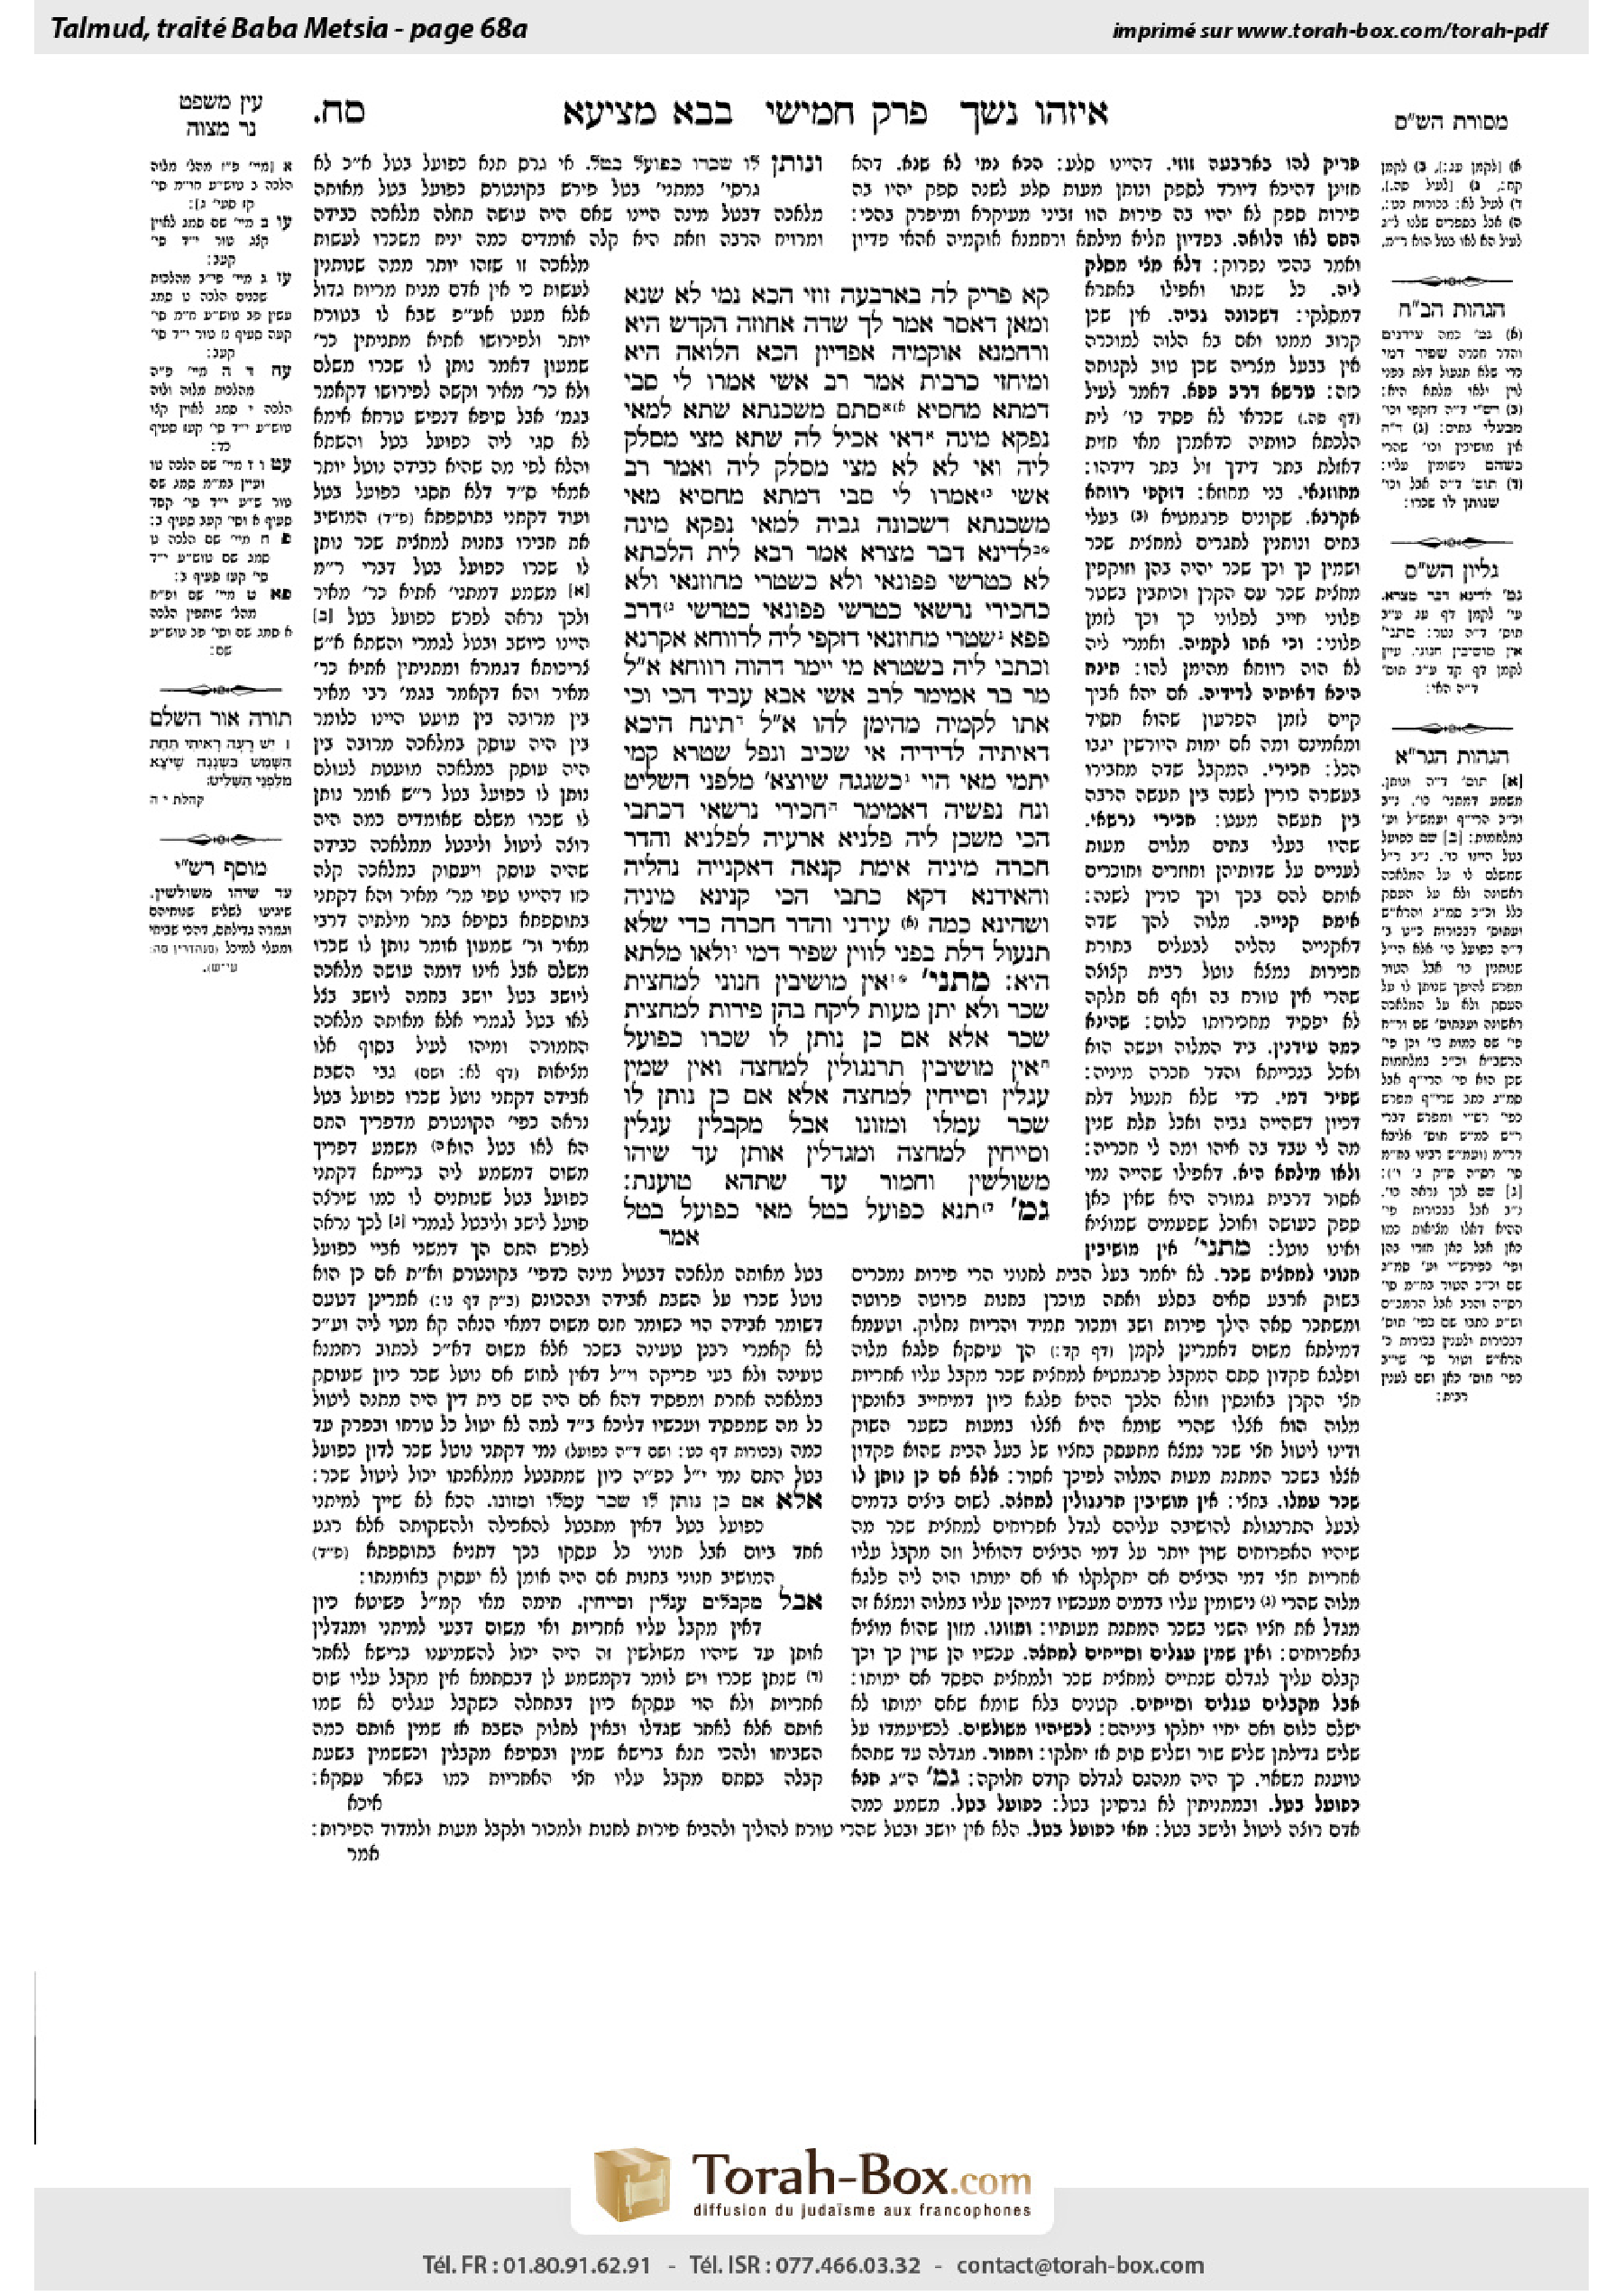
Scan : Torah-Box. Daf Study est un projet indépendant, sans affiliation ni approbation de Torah-Box ou de Sefaria.