Baba Batra 174b en français · בבא בתרא קע״ד ב
Traduction française du daf 174b du traité Baba Batra (Bava Batra 174b en anglais), avec le texte araméen, l’anglais de Sefaria et le scan de la page, pour étudier le Daf Yomi.
Ouvrir dans le lecteur interactifLire le daf du jour
Traduction française de Baba Batra 174b
Les traductions françaises de Daf Study sont générées par IA à partir de l’édition anglaise de Sefaria. Elles peuvent contenir des erreurs : vérifie toujours un passage avec le texte source.
La Guemara demande : Quelle est la différence entre l’opinion de Rav Pappa et celle de Rav Houna, fils de Yehoshoua, puisque tous deux conviennent que les orphelins sont dispensés de rembourser la dette jusqu’à leur majorité ?
La Guemara répond : La différence entre eux apparaît dans le cas où le débiteur, c’est-à-dire le défunt, reconnaît explicitement, juste avant sa mort, qu’il n’a encore remboursé aucune partie de son emprunt. Une autre différence apparaît dans le cas où le tribunal a mis le défunt au herem parce qu’il ne coopérait pas avec lui pour rembourser sa dette, et où il est mort alors qu’il était toujours sous le coup du herem, ce qui montre que la dette n’avait pas été remboursée avant sa mort. Dans ces deux cas, Rav Pappa dispenserait les orphelins mineurs du paiement, car les mineurs ne sont pas tenus d’accomplir les mitsvot, tandis que Rav Houna, fils de Yehoshoua, leur imposerait de rembourser immédiatement la dette, puisqu’il est impossible que leur père l’ait remboursée.
Les Sages d’Erets Israël envoyèrent de là-bas en Babylonie une décision : dans le cas où le tribunal avait mis un débiteur au herem parce qu’il ne coopérait pas au remboursement de sa dette, et où le débiteur était mort alors qu’il était toujours sous le coup du herem, la halakha suit l’opinion de Rav Houna, fils de Rav Yehoshoua, et les orphelins doivent rembourser immédiatement la dette.
La Guemara soulève une objection à partir d’une baraïta (Tossefta 11:15) : un garant d’une dette qui détient le billet de cette dette, attestant qu’il l’a remboursée, et qui demande maintenant au débiteur de le rembourser, ne peut pas se faire payer si le débiteur est mort et que l’obligation de rembourser la dette est échue à ses héritiers mineurs. Mais si le créancier a écrit dans le billet : « J’ai reçu de toi, le garant, le remboursement », alors le garant peut recouvrer la dette auprès des héritiers mineurs.
La Guemara explique l’objection : il est vrai que, selon l’opinion de Rav Houna, fils de Rav Yehoshoua, on peut trouver un cas où les héritiers mineurs seraient tenus de rembourser la dette, par exemple lorsque le débiteur, c’est-à-dire le défunt, reconnaît explicitement, juste avant sa mort, qu’il n’a pas encore remboursé l’emprunt. Mais selon l’opinion de Rav Pappa, qui soutient que les héritiers mineurs n’ont jamais à rembourser les dettes de leur père, cela pose problème. De quel cas la baraïta parle-t-elle ?
La Guemara répond : Ce cas est différent, car c’est pour cette raison que le créancier s’est donné la peine d’écrire au garant : « J’ai reçu de toi le remboursement. » Dès lors que le créancier l’écrit dans le billet, celui-ci acquiert le statut d’un billet de dette détenu directement par le garant contre le débiteur ; même Rav Pappa convient qu’une dette consignée dans un billet peut être recouvrée immédiatement sur les biens du défunt, même auprès des héritiers mineurs.
La Guemara rapporte : un certain garant s’était porté garant d’un emprunt accordé par un non-Juif. Il remboursa le créancier non juif avant que celui-ci ne réclame le remboursement aux orphelins laissés par le débiteur. Le garant demanda alors aux orphelins de le rembourser. Rav Mordekhaï dit à Rav Ashi : Voici ce qu’Avimi de Hagronya a dit au nom de Rava : même selon celui qui dit que nous tenons compte de la possibilité que le défunt ait remis des liasses d’argent au créancier avant sa mort, cette affirmation ne vaut que dans le cas d’un créancier juif. Mais dans le cas d’un créancier non juif, puisque, selon la loi des non-Juifs, il a le droit de s’adresser directement à un garant, nous ne tenons pas compte de la possibilité que le défunt ait remis des liasses d’argent. Le débiteur ne rembourserait pas le non-Juif avant l’échéance de l’emprunt, puisque celui-ci a le droit de recouvrer directement auprès du garant et qu’il recevrait ainsi un double paiement.
Rav Ashi dit à Rav Mordekhaï : Au contraire, même selon celui qui dit que nous ne tenons pas compte de la possibilité que le défunt ait remis des liasses d’argent, cette affirmation ne vaut que dans le cas d’un créancier juif. Mais dans le cas d’un créancier non juif, puisque, selon la loi des non-Juifs, il a le droit de s’adresser directement à un garant, aucun garant n’accepterait de se porter garant d’un tel emprunt si le débiteur n’avait pas remis d’emblée des liasses d’argent au créancier non juif à titre de garantie.
§ La Michna enseigne : et ainsi Rabban Shimon ben Gamliel disait : si un garant s’est engagé pour la kétouba d’une femme et que son mari la divorce, le mari doit prononcer un vœu lui interdisant de tirer le moindre profit d’elle, de sorte qu’il ne puisse jamais se remarier avec elle. La Guemara rapporte un incident lié à cette décision : un certain Moshe bar Atzari s’était porté garant de la kétouba de sa belle-fille, garantissant la somme promise par son fils en cas de décès ou de divorce. Son fils, nommé Rav Houna, était un jeune érudit en Torah et se trouvait dans une situation financière précaire. Abayé dit : N’y a-t-il personne pour aller conseiller à Rav Houna de divorcer de sa femme, afin qu’elle puisse réclamer sa kétouba au père de Rav Houna, puis que Rav Houna se remarie avec elle ?
Rava dit à Abayé : Mais n’avons-nous pas appris dans la Michna que, dans de telles circonstances, lorsqu’un mari divorce de sa femme, il doit prononcer un vœu lui interdisant de tirer le moindre profit d’elle, ce qui exclut la possibilité de se remarier avec elle ? Abayé lui dit : Cela veut-il dire que tout homme qui divorce de sa femme le fait devant un tribunal ? On pourrait conseiller à Rav Houna de divorcer de sa femme hors du tribunal, auquel cas il pourrait le faire sans être contraint de prononcer le vœu prescrit.
Finalement, on découvrit que ce Rav Houna était prêtre et qu’il ne pouvait pas épouser une divorcée, pas même son ancienne épouse. La suggestion d’Abayé n’était donc pas envisageable pour lui. En l’apprenant, Abayé dit : Cela correspond au proverbe que les gens citent : la pauvreté poursuit les pauvres.
La Guemara demande : Mais Abayé a-t-il vraiment dit cela ? Aurait-il réellement encouragé à donner un tel conseil ? Abayé ne dit-il pas lui-même : Qui est un homme rusé et méchant ? Celui qui conseille de vendre un bien conformément à la décision de Rabban Shimon ben Gamliel. Comme cela est enseigné ailleurs (Ketoubot 95b), si quelqu’un dit : « Mon bien t’est légué, et après ta mort, il reviendra à untel », Rabban Shimon ben Gamliel décide que le premier bénéficiaire peut vendre le bien, privant ainsi le second bénéficiaire de la possibilité de le recevoir. Abayé disait que conseiller à quelqu’un d’agir ainsi, bien que cela soit légal, est considéré comme méchant. Ici aussi, pourquoi aurait-il conseillé à Rav Houna de divorcer de sa femme dans le seul but de contraindre son père à payer la kétouba ?
La Guemara répond : Lorsqu’il s’agit de son fils, c’est différent. Contraindre un père à donner de l’argent à son propre fils n’est pas considéré comme de la méchanceté. De plus, lorsqu’il s’agit d’un érudit en Torah, c’est différent. Lui procurer de l’argent n’est pas considéré comme de la méchanceté, car cet argent lui permet de poursuivre ses études.
La Guemara pose une autre question au sujet de cet incident : Mais Moshe bar Atzari n’était-il pas un garant ? Or, nous tenons pour établi, comme la Guemara le soulignera bientôt, qu’un garant d’une kétouba n’est pas tenu de la payer. La Guemara répond : Il était un garant inconditionnel.
La Guemara objecte : Cela s’explique bien selon celui qui dit qu’un garant inconditionnel d’une kétouba est tenu de la payer même si le mari ne possède aucun bien au moment du mariage. Selon cette opinion, tout va bien. Mais selon celui qui dit : si le mari possède des biens, le garant inconditionnel est tenu de payer, mais s’il n’en possède pas, il n’est pas tenu de le faire, que peut-on répondre ? Rav Houna ne possédait manifestement aucun bien. Pourquoi, alors, son père était-il tenu de payer sa kétouba, selon cette dernière opinion ?
La Guemara répond : Si tu le souhaites, dis que Rav Houna possédait des biens lorsqu’il s’est marié, de sorte que la garantie de son père a pris effet, mais que ces biens ont été ruinés, c’est-à-dire qu’ils ont été détériorés ou perdus entre-temps. Et si tu le souhaites, dis plutôt qu’un père, à l’égard de son fils, s’engage sincèrement à garantir sa kétouba, même si le fils ne possède aucun bien.
La Guemara développe la question en discussion. Car il a été enseigné : tous conviennent qu’un garant ordinaire d’une kétouba n’est pas tenu de payer la kétouba, et tous conviennent qu’un garant inconditionnel d’un créancier, c’est-à-dire d’un prêt, est tenu de rembourser le prêt. Les Sages sont en désaccord au sujet du garant inconditionnel d’une kétouba et du garant ordinaire d’un créancier. Un Sage estime que, si le débiteur ou le mari possède des biens, ces garants sont tenus de respecter les engagements qu’ils ont pris, mais que, s’il ne possède aucun bien, le garant n’est pas tenu de payer. Un autre Sage estime que, que le débiteur ou le mari possède ou non des biens, le garant est tenu de payer.
Et la halakha est qu’un garant est tenu de payer, que le débiteur possède ou non des biens. Cela exclut le garant d’une kétouba, auquel cas, même si le mari possède des biens, il n’est pas tenu de payer. Pour quelle raison ? Le garant entend accomplir la mitsva de faciliter un mariage en encourageant la femme à y consentir grâce à son intervention, mais il n’a pas véritablement l’intention de s’engager à payer. En outre, contrairement au garant d’un prêt, pour qui le créancier subirait une perte s’il n’était pas remboursé, la femme ne subit aucune perte concrète, puisque le mari ne lui emprunte pas d’argent. Le degré d’engagement du garant est donc moindre dans ce cas. C’est pourquoi les Sages ont institué que le garant n’est pas tenu de payer la kétouba sur ses propres biens.
§ Rav Houna dit qu’une personne sur son lit de mort qui a consacré tous ses biens au Trésor du Temple, puis déclare : « Untel a cent dinars chez moi », c’est-à-dire : « Je dois cent dinars à untel », est considérée comme digne de foi, et l’argent doit être remboursé à cette personne. La raison en est qu’il existe une présomption selon laquelle une personne ne complote pas au détriment du Trésor du Temple. Elle ne mentirait pas en prétendant devoir de l’argent à quelqu’un, causant ainsi une perte au Trésor du Temple.
Rav Naḥman objecte à cette décision : Une personne complote-t-elle au détriment de ses enfants ? Bien sûr que non. Pourtant, Rav et Shmuel disent tous deux que, lorsqu’une personne sur son lit de mort déclare : « Untel a cent dinars chez moi », ses enfants ne les lui donnent que si elle a explicitement dit : « Donnez-lui l’argent » ; si elle ne l’a pas dit explicitement, ils ne le lui donnent pas. On ne suppose pas que la personne sur son lit de mort dise la vérité au sujet de cette dette, à moins qu’elle n’ordonne explicitement que l’argent soit donné. Il semble donc qu’on suppose qu’une personne est susceptible de faire de fausses déclarations afin que ses fils ne paraissent pas rassasiés, c’est-à-dire riches. Une personne sur son lit de mort peut prétendre à tort être endettée afin de dissiper l’idée que ses enfants sont des héritiers fortunés.
Texte source et traduction anglaise
בבא בתרא קע״ד ב · texte araméen et hébreu
מַאי בֵּינַיְיהוּ?
אִיכָּא בֵּינַיְיהוּ כְּשֶׁחַיָּיב מוֹדֶה. אִי נָמֵי, דְּשַׁמְּתוּהוּ וּמִת בְּשַׁמְתֵּיהּ.
שְׁלַחוּ מִתָּם: שַׁמְּתוּהוּ וּמִת בְּשַׁמְתֵּיהּ, הִלְכְתָא כְּרַב הוּנָא בְּרֵיהּ דְּרַב יְהוֹשֻׁעַ.
מֵיתִיבִי: עָרֵב שֶׁהָיָה שְׁטַר חוֹב יוֹצֵא מִתַּחַת יָדוֹ – אֵינוֹ גּוֹבֶה. וְאִם כָּתוּב בּוֹ: ״הִתְקַבַּלְתִּי מִמְּךָ״ – גּוֹבֶה.
בִּשְׁלָמָא לְרַב הוּנָא בְּרֵיהּ דְּרַב יְהוֹשֻׁעַ – מַשְׁכַּחַתְּ לַהּ כְּשֶׁחַיָּיב מוֹדֶה, אֶלָּא לְרַב פָּפָּא – קַשְׁיָא!
שָׁאנֵי הָתָם, לְהָכִי טְרַח וּכְתַב לֵיהּ ״הִתְקַבַּלְתִּי״.
הָהוּא עָרְבָא דְּגוֹי דְּפַרְעֵיהּ לְגוֹי מִקַּמֵּי דְּלִתְבְּעִינְהוּ לְיַתְמֵי. אֲמַר לֵיהּ רַב מָרְדֳּכַי לְרַב אָשֵׁי, הָכִי אָמַר אֲבִימִי מֵהַגְרוֹנְיָא מִשְּׁמֵיהּ דְּרָבָא: אֲפִילּוּ לְמַאן דְּאָמַר חָיְישִׁינַן לִצְרָרֵי – הָנֵי מִילֵּי יִשְׂרָאֵל; אֲבָל גּוֹי, כֵּיוָן דְּבָתַר עָרְבָא אָזֵיל – לָא חָיְישִׁינַן לִצְרָרֵי.
אֲמַר לֵיהּ: אַדְּרַבָּה! אֲפִילּוּ לְמַאן דְּאָמַר לָא חָיְישִׁינַן לִצְרָרֵי – הָנֵי מִילֵּי יִשְׂרָאֵל; אֲבָל גּוֹיִם, כֵּיוָן דְּדִינַיְיהוּ בָּתַר עָרְבָא אָזְלִי, אִי לָאו דְּאַתְפְּסֵיהּ צְרָרֵי מֵעִיקָּרָא – לָא הֲוָה מְקַבֵּל לֵיהּ.
וְכֵן הָיָה רַבָּן שִׁמְעוֹן בֶּן גַּמְלִיאֵל אוֹמֵר: הֶעָרֵב לְאִשָּׁה בִּכְתוּבָּתָהּ [וְכוּ׳]. מֹשֶׁה בַּר עַצְרִי עָרְבָא דִּכְתוּבְּתַהּ דְּכַלָּתֵיהּ הֲוָה. רַב הוּנָא בְּרֵיהּ – צוּרְבָּא מִדְּרַבָּנַן הֲוָה, וּדְחִיקָא לֵיהּ מִילְּתָא. אָמַר אַבָּיֵי: לֵיכָּא דְּנֵיזִיל דְּנַסְּבֵיהּ עֵצָה לְרַב הוּנָא, דִּנְגָרְשַׁהּ לִדְבֵיתְהוּ וְתֵיזִיל וְתִגְבֵּי כְּתוּבָּה מֵאֲבוּהּ, וַהֲדַר נַהְדְּרַהּ?
אֲמַר לֵיהּ רָבָא: וְהָא ״יַדִּירֶנָּה הֲנָאָה״ תְּנַן! אֲמַר לֵיהּ אַבָּיֵי: אַטּוּ כֹּל דִּמְגָרֵשׁ – בְּבֵי דִינָא מְגָרֵשׁ?
לְסוֹף אִיגַּלַּאי מִילְּתָא דְּכֹהֵן הוּא. אָמַר אַבָּיֵי, הַיְינוּ דְאָמְרִי אִינָשֵׁי: בָּתַר עַנְיָא אָזְלָא עַנְיוּתָא.
וּמִי אָמַר אַבָּיֵי הָכִי? וְהָא אָמַר אַבָּיֵי: אֵיזֶהוּ ״רָשָׁע עָרוּם״? זֶה הַמַּשִּׂיא עֵצָה לִמְכּוֹר בִּנְכָסִים כְּרַבָּן שִׁמְעוֹן בֶּן גַּמְלִיאֵל!
בְּנוֹ שָׁאנֵי, וְצוּרְבָּא מֵרַבָּנַן שָׁאנֵי.
וְהָא עָרֵב הוּא, [וְקַיְימָא לַן] עָרֵב דִּכְתוּבָּה לֹא מִשְׁתַּעְבֵּד! קַבְּלָן הֲוָה.
הָנִיחָא לְמַאן דְּאָמַר: קַבְּלָן דִּכְתוּבָּה – אַף עַל גַּב דְּלֵית לֵיהּ נִכְסֵי לְבַעַל, מִשְׁתַּעְבַּד – שַׁפִּיר. אֶלָּא לְמַאן דְּאָמַר: אִי אִית לֵיהּ מִשְׁתַּעְבַּד, אִי לֵית לֵיהּ לָא מִשְׁתַּעְבַּד – מַאי אִיכָּא לְמֵימַר?
אִיבָּעֵית אֵימָא: מִיהְוֵי הֲוָה לֵיהּ, וְאִישְׁתְּדוּף. וְאִיבָּעֵית אֵימָא: אַבָּא לְגַבֵּי בְּרֵיהּ – שַׁעְבּוֹדֵי מְשַׁעְבַּד נַפְשֵׁיהּ.
דְּאִיתְּמַר: עָרֵב דִּכְתוּבָּה – דִּבְרֵי הַכֹּל לָא מִשְׁתַּעְבַּד. קַבְּלָן דְּבַעַל חוֹב – דִּבְרֵי הַכֹּל מִשְׁתַּעְבַּד. קַבְּלָן דִּכְתוּבָּה, וְעָרֵב דְּבַעַל חוֹב – פְּלִיגִי; מָר סָבַר: אִי אִית לֵיהּ נִכְסֵי לְלֹוֶה – מִשְׁתַּעְבַּד, אִי לֵית לֵיהּ – לָא מִשְׁתַּעְבַּד; וּמָר סָבַר: בֵּין אִית לֵיהּ וּבֵין לֵית לֵיהּ – מִשְׁתַּעְבַּד.
וְהִלְכְתָא: עָרֵב – בֵּין אִית לֵיהּ וּבֵין לֵית לֵיהּ, מִשְׁתַּעְבַּד; בַּר מֵעָרֵב דִּכְתוּבָּה – דְּאַף עַל גַּב דְּאִית לֵיהּ לְבַעַל, לָא מִשְׁתַּעְבַּד. מַאי טַעְמָא? מִצְוָה הוּא דַּעֲבַד, וְלָאו מִידֵּי חַסְּרֵהּ.
אָמַר רַב הוּנָא: שְׁכִיב מְרַע שֶׁהִקְדִּישׁ כׇּל נְכָסָיו, וְאָמַר ״מָנֶה לִפְלוֹנִי בְּיָדִי״ – נֶאֱמָן; חֲזָקָה אֵין אָדָם עוֹשֶׂה קְנוּנְיָא עַל הֶקְדֵּשׁ.
מַתְקֵיף לַהּ רַב נַחְמָן: וְכִי אָדָם עוֹשֶׂה קְנוּנְיָא עַל בָּנָיו?! דְּרַב וּשְׁמוּאֵל דְּאָמְרִי תַּרְוַיְיהוּ: שְׁכִיב מְרַע שֶׁאָמַר ״מָנֶה לִפְלוֹנִי בְּיָדִי״; אָמַר ״תְּנוּ״ – נוֹתְנִין. לֹא אָמַר ״תְּנוּ״ – אֵין נוֹתְנִין. אַלְמָא אָדָם עָשׂוּי שֶׁלֹּא לְהַשְׂבִּיעַ אֶת בָּנָיו;
Bava Batra 174b · traduction anglaise de Sefaria
The Gemara asks: What is the difference between the opinion of Rav Pappa and that of Rav Huna, son of Yehoshua, as both agree that the orphans are exempt from repaying the debt until they reach majority?
The Gemara answers: The difference between them is in a case where the one who owed the money, i.e., the deceased, admits explicitly just before his death that he did not yet repay any of his loan. Alternatively, there is a difference between them in a case where the court excommunicated the deceased for not cooperating with the court in repaying his debt, and he died while still in a state of excommunication, which demonstrates that the debt had not been repaid prior to his death. In both of these cases Rav Pappa would exempt the minor orphans from payment, as minors are not obligated to perform mitzvot, while Rav Huna, son of Yehoshua, would require them to repay the debt immediately, as there is no possibility that their father had repaid the debt.
The Sages of Eretz Yisrael sent a ruling from there to Babylonia: In a case where the court had excommunicated a debtor for not cooperating in repaying his debt, and the debtor died while still in a state of excommunication, the halakha is in accordance with the opinion of Rav Huna, son of Rav Yehoshua, and the orphans must repay the debt immediately.
The Gemara raises an objection from a baraita (Tosefta 11:15): A guarantor for a debt who has the promissory note for that debt in his possession, indicating that he has repaid the debt, and now seeks reimbursement from the debtor, cannot collect if the debtor has died and the obligation for the debt has fallen to his minor heirs. But if it is written by the creditor in the promissory note: I received repayment from you, the guarantor, then the guarantor can collect the debt from the minor heirs.
The Gemara explains the objection: Granted, according to the opinion of Rav Huna, son of Rav Yehoshua, you find a case where the minor heirs would be required to repay the debt, such as when the one who owed the money, i.e., the deceased, admits explicitly just before his death that he did not yet repay the loan. But according to the opinion of Rav Pappa, who maintains that minor heirs never have to repay their father’s debts, it is difficult. What is the case discussed in the baraita?
The Gemara answers: It is different there, as it is for this reason that the creditor troubled himself and wrote for the guarantor: I received repayment from you. Once the creditor writes this in the promissory note, it attains the status of a promissory note of the guarantor held directly against the debtor, and even Rav Pappa agrees that a debt that is recorded in a promissory note can be collected from the deceased’s property immediately, even from the minor heirs.
The Gemara relates: There was a certain guarantor who had guaranteed a loan given by a gentile, who repaid the gentile creditor before the gentile creditor claimed repayment from the orphans who survived the debtor. The guarantor now sought reimbursement from the orphans. Rav Mordekhai said to Rav Ashi: This is what Avimi of Hagronya said in the name of Rava: Even according to the one who says that we are concerned for the possibility that the deceased may have given bundles of money to the creditor before his death, this statement applies only in the case of a Jewish creditor. But in the case of a gentile creditor, since according to gentile law he is entitled to go directly to a guarantor, we are not concerned for the possibility that the deceased may have given bundles of money. The debtor would not repay the gentile before the loan is due, as the latter has the right to collect directly from the guarantor, and would thereby receive double payment.
Rav Ashi said to Rav Mordekhai: On the contrary, even according to the one who says that we are not concerned for the possibility that the deceased may have given bundles of money, this statement applies only in the case of a Jewish creditor. But in the case of a gentile creditor, since according to gentile law they are entitled to go directly to a guarantor, no guarantor would accept upon himself to guarantee such a loan if the debtor had not given bundles of money as collateral to the gentile creditor from the outset.
§ The mishna teaches: And so Rabban Shimon ben Gamliel would say: If there is a guarantor for a woman for her marriage contract, and her husband is divorcing her, the husband must take a vow prohibiting himself from deriving any benefit from her so that he can never remarry her. The Gemara relates an incident pertaining to this ruling: Someone named Moshe bar Atzari was a guarantor for the marriage contract of his daughter-in-law, guaranteeing the money promised by his son in the event of death or divorce. His son, named Rav Huna, was a young Torah scholar, and was in financial straits. Abaye said: Is there no one who will go advise Rav Huna that he should divorce his wife, and she will go and collect her marriage contract from Rav Huna’s father, and then Rav Huna should remarry her?
Rava said to Abaye: But didn’t we learn in the mishna that when a husband divorces his wife in such circumstances he must take a vow prohibiting himself from deriving any benefit from her, thereby precluding the possibility of remarriage? Abaye said to him: Is that to say that everyone who divorces his wife divorces her in a court? Rav Huna could be advised to divorce his wife outside the court, in which case he could do so without being forced to take the prescribed vow.
Ultimately, it was revealed that this Rav Huna was a priest, who may not marry a divorcée, even his own ex-wife. Abaye’s suggestion was therefore not an option for him. Upon hearing this, Abaye said: This is in accordance with the adage that people say: Poverty follows the poor.
The Gemara asks: But did Abaye really say this? Would he really encourage giving such advice? But doesn’t Abaye himself say: Who is a cunning, wicked person? This is one who provides advice to sell property in accordance with the ruling of Rabban Shimon ben Gamliel. As taught elsewhere (Ketubot 95b), if one says: My property is hereby bequeathed to you, and after you die it will pass to so-and-so, Rabban Shimon ben Gamliel rules that the first recipient can sell the property, which would thereby deprive the second recipient from receiving it. Abaye said that giving advice to someone to pursue such action, though it is legally sound, is considered wicked. Here as well, why would he give advice to Rav Huna to divorce his wife only in order to force his father to pay the marriage contract?
The Gemara answers: When dealing with one’s son it is different. It is not considered wickedness to force a father to give money to his own son. Moreover, when dealing with a Torah scholar it is different. It is not considered wickedness to procure money for a Torah scholar, because the money enables him to pursue his studies.
The Gemara asks another question with regard to this incident: But wasn’t Moshe bar Atzari a guarantor? And we maintain, as the Gemara will soon note, that a guarantor for a marriage contract does not become obligated to pay. The Gemara answers: He was an unconditional guarantor.
The Gemara objects: This works out well according to the one who says that an unconditional guarantor for a marriage contract becomes obligated to pay it even if the husband has no property of his own at the time of the marriage. According to this opinion all is well. But according to the one who says: If the husband has his own property the unconditional guarantor becomes obligated to pay, but if the husband does not have his own property he does not become obligated, what is there to say? Rav Huna obviously did not have any property of his own. Why, then, was his father held responsible for paying his marriage contract according to this latter opinion?
The Gemara answers: If you wish, say that Rav Huna had property when he got married, so that his father’s guarantee took effect, but it became blighted, i.e., it was ruined or lost in the interim. And if you wish, say instead: A father, vis-à-vis his son, sincerely obligates himself to guarantee his marriage contract, even when the son has no property of his own.
The Gemara elaborates on the issue under discussion. This is as it was stated: Everyone agrees that a standard guarantor for a marriage contract does not become obligated to pay the marriage contract, and everyone agrees that an unconditional guarantor for a creditor, i.e., for a loan, becomes obligated to repay the loan. With regard to an unconditional guarantor for a marriage contract and a standard guarantor for a creditor, the Sages disagree. One Sage holds that if the debtor or husband has his own property, these guarantors become obligated for the guarantees they have undertaken, but if he does not have his own property the guarantor does not become obligated. And one Sage holds that whether the debtor or husband has property or does not have property, the guarantor becomes obligated to pay it.
And the halakha is that a guarantor becomes obligated to pay, whether the debtor has his own property or does not have property. This is to the exclusion of a guarantor for a marriage contract, in which case even if the husband has his own property he does not become obligated to pay. What is the reason for this? The intention of the guarantor is to perform the mitzva of facilitating a marriage by encouraging the woman to consent to the marriage as a result of his involvement, but he does not truly intend to obligate himself. And furthermore, in contrast to a guarantor for a loan, where the creditor stands to suffer a loss if he is not repaid, the woman does not suffer any concrete loss, as the husband does not borrow money from the woman. Therefore, the level of commitment of the guarantor in this case is lower. Accordingly, the Sages instituted that the guarantor does not become responsible for payment of the marriage contract from his own property.
§ Rav Huna says that a person on his deathbed who consecrated all his property to the Temple treasury, and then says: So-and-so has one hundred dinars in my possession, i.e., I owe one hundred dinars to so-and-so, is deemed credible, and the money is to be repaid to that person. The reason for this is that there is a presumption that a person does not collude against the Temple treasury. He would not lie about owing money to someone, thereby causing a loss to the Temple treasury.
Rav Naḥman objects to this ruling: And does a person collude against his children? Of course not. Yet, as Rav and Shmuel both say that in the case of a person on his deathbed who says: So-and-so has one hundred dinars in my possession, only if he says explicitly: Give him the money, the children give it, but if he did not say explicitly: Give him the money, the children do not give it. The person on his deathbed is not assumed to be telling the truth about owing the money unless he explicitly instructs that the money be given. Apparently, then, it is assumed that a person is prone to make false statements so as not to make his sons appear sated, i.e., wealthy. A person on his deathbed may falsely claim that he is in debt in order to dispel the notion that his children are wealthy heirs.
Texte de Sefaria : William Davidson Edition - Vocalized Aramaic (CC BY NC) ; William Davidson Edition - English (CC BY NC).
Scan de Baba Batra 174b
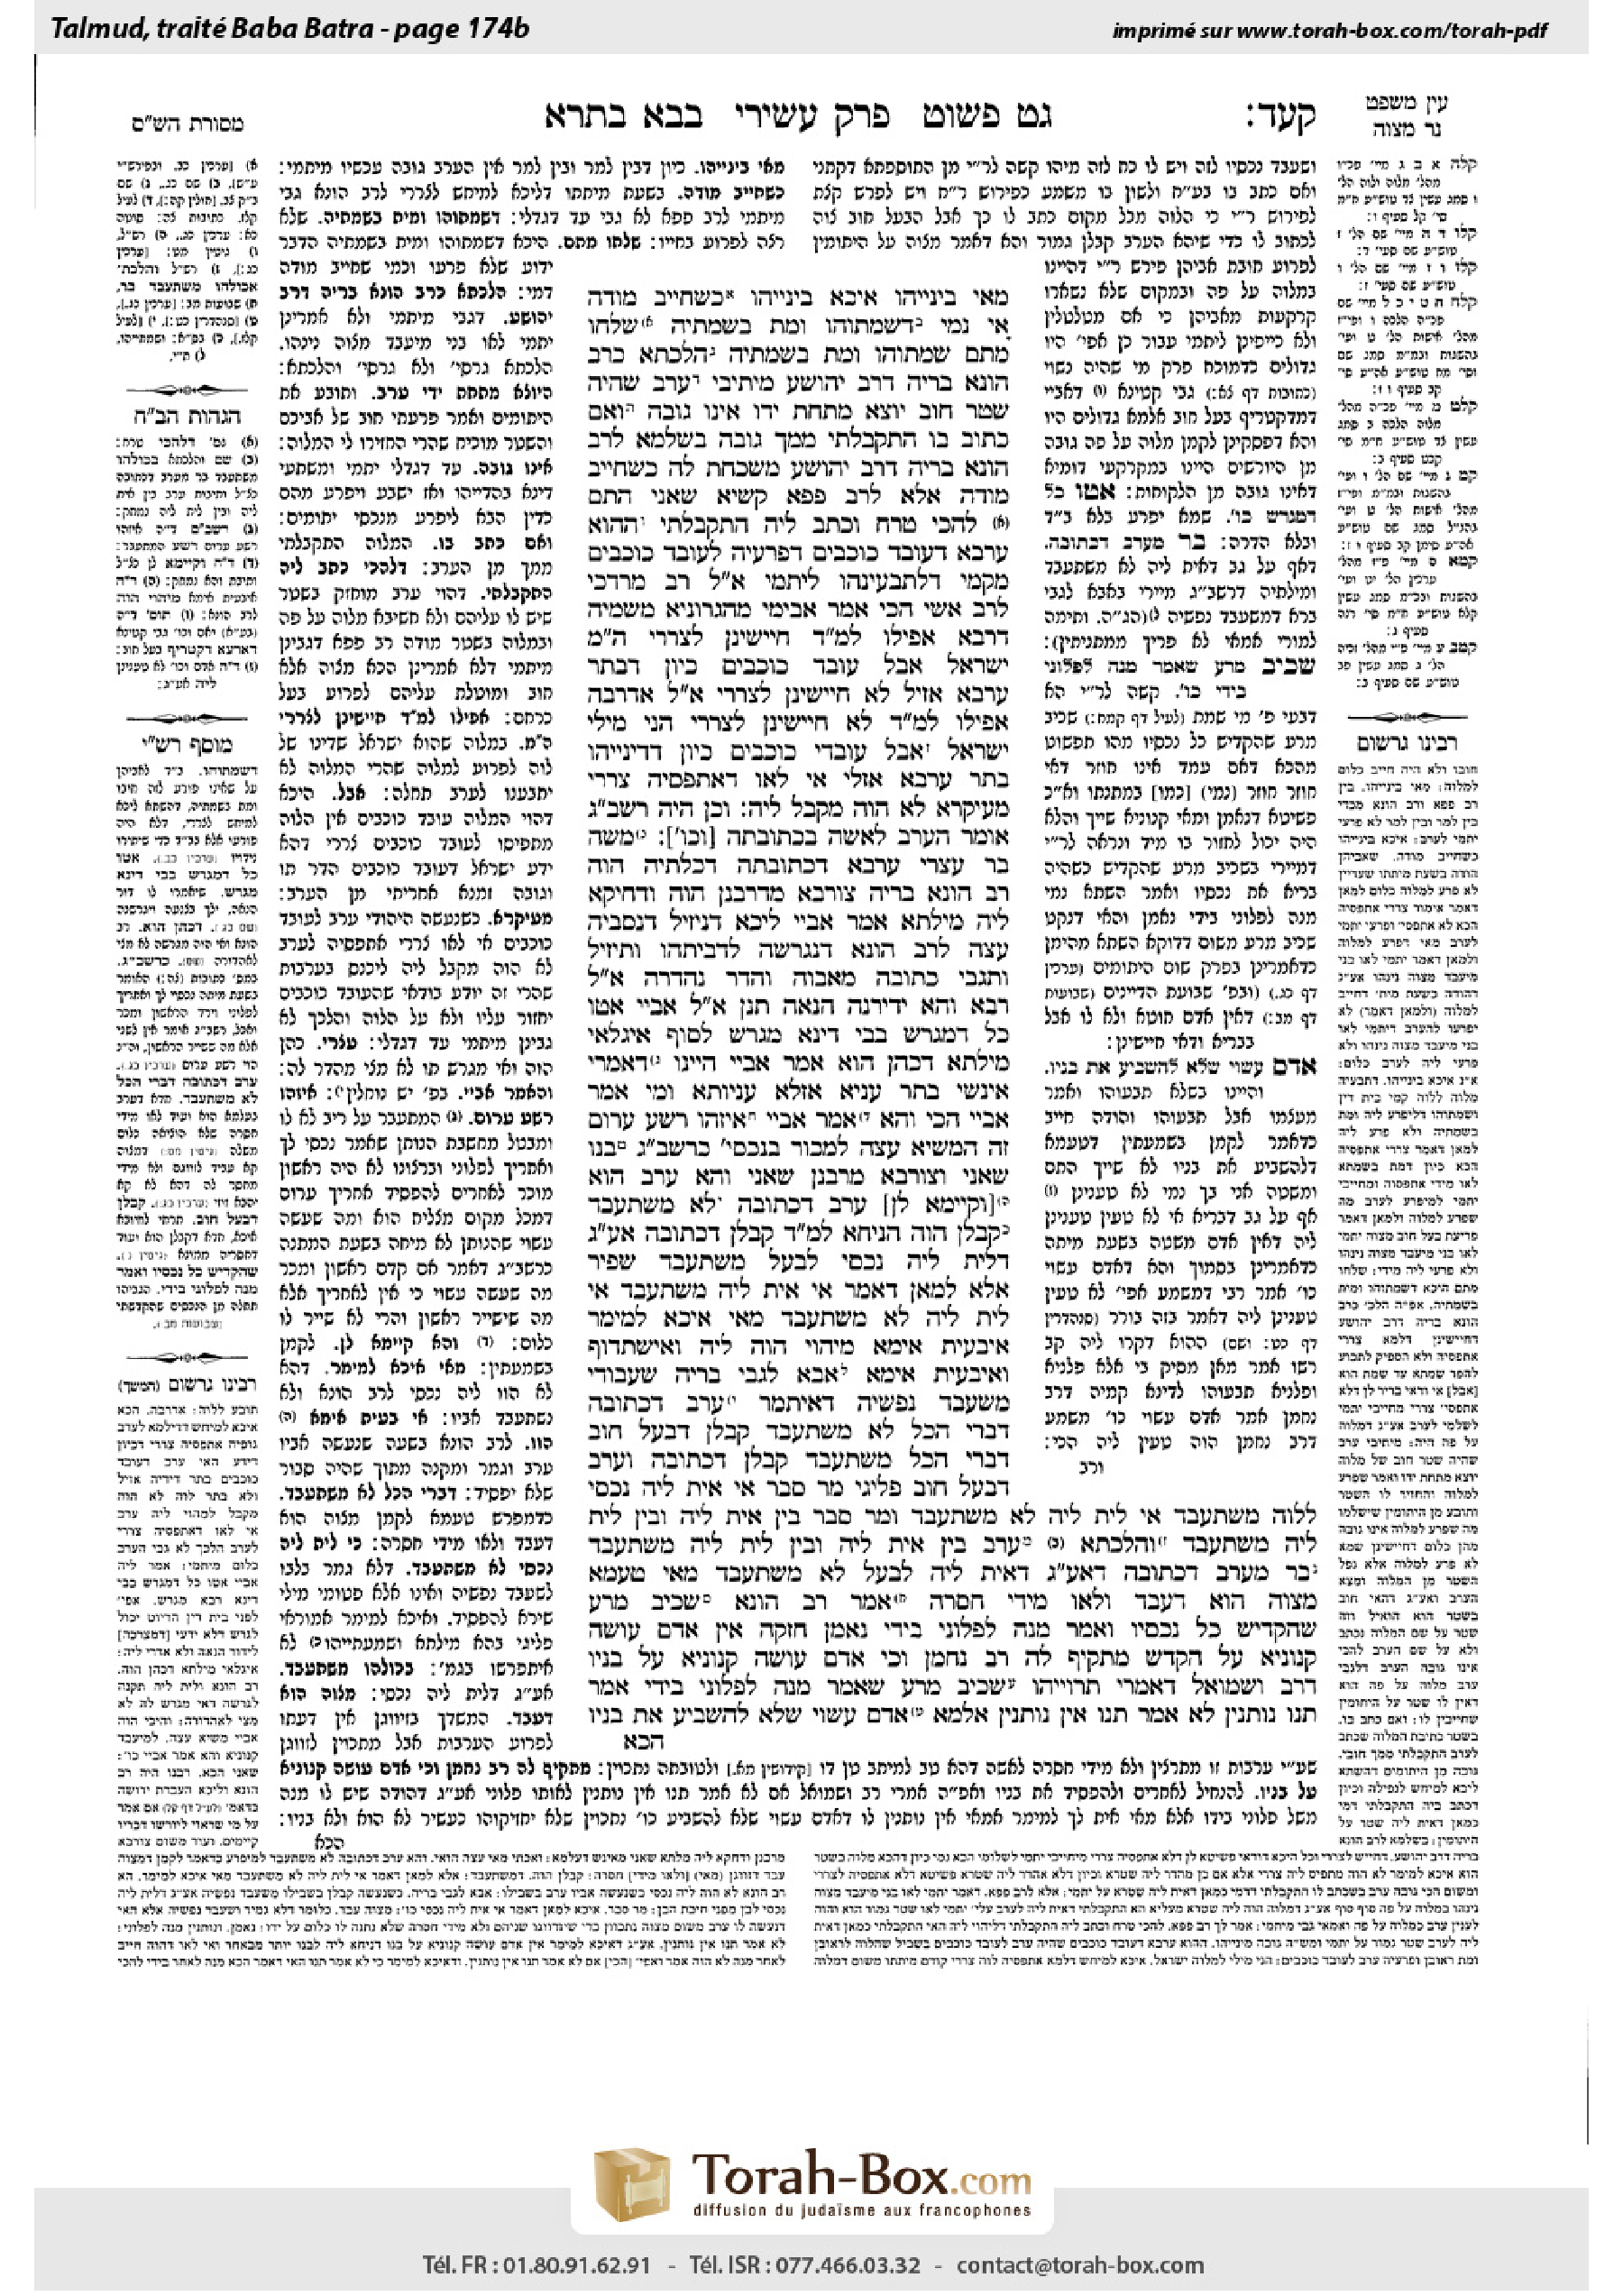
Scan : Torah-Box. Daf Study est un projet indépendant, sans affiliation ni approbation de Torah-Box ou de Sefaria.