Baba Metsia 72a en français · בבא מציעא ע״ב א
Traduction française du daf 72a du traité Baba Metsia (Bava Metzia 72a en anglais), avec le texte araméen, l’anglais de Sefaria et le scan de la page, pour étudier le Daf Yomi.
Ouvrir dans le lecteur interactifLire le daf du jour
Traduction française de Baba Metsia 72a
Les traductions françaises de Daf Study sont générées par IA à partir de l’édition anglaise de Sefaria. Elles peuvent contenir des erreurs : vérifie toujours un passage avec le texte source.
Néanmoins, en vertu du droit rabbinique, n’a-t-il pas le pouvoir d’acquérir un bien au moyen d’un acte d’acquisition effectué par un tiers ? Ici aussi, il n’en va pas autrement : le Juif peut effectuer un acte d’acquisition au nom du non-Juif, même s’il n’y a pas de représentation pour les non-Juifs.
La Guemara rejette cette comparaison : Mais il n’en est pas ainsi. Un mineur juif parviendra un jour à être habilité à agir comme représentant, tandis qu’un non-Juif ne pourra jamais être habilité à agir comme représentant. Par conséquent, les Sages n’ont pas institué pour les non-Juifs le pouvoir d’acquérir un bien au moyen d’un acte d’acquisition effectué par un Juif.
§ Les Sages ont enseigné : Dans le cas d’un Juif qui a emprunté de l’argent à un non-Juif avec intérêt, si le prêteur non-juif a ajouté les intérêts au principal et les a réunis en une seule dette pour l’emprunteur juif, puis s’est converti, la halakha dépend des circonstances. Si le non-Juif a ainsi constitué la dette avant sa conversion, il peut recouvrer le principal auprès de l’emprunteur et peut aussi recouvrer les intérêts. Puisque ceux-ci avaient déjà été réunis au principal en une seule dette, c’est comme s’il avait déjà perçu les intérêts alors qu’il était encore non-Juif. Mais s’il a ainsi constitué la dette après sa conversion, il peut recouvrer le principal, mais pas les intérêts, car ceux-ci avaient encore le statut d’intérêts lorsqu’il est devenu juif.
De même, dans le cas d’un non-Juif qui a emprunté de l’argent à un Juif avec intérêt, si le prêteur juif a ajouté les intérêts au principal et les a réunis en une seule dette pour l’emprunteur non-juif, puis que celui-ci s’est converti, si le prêteur a ainsi constitué la dette avant la conversion, le Juif peut recouvrer le principal et aussi les intérêts. S’il a ainsi constitué la dette pour le non-Juif après sa conversion, il peut recouvrer le principal, mais pas les intérêts, car ceux-ci avaient encore le statut d’intérêts lorsque l’emprunteur est devenu juif.
La baraïta poursuit : Rabbi Yossei dit : Si un non-Juif a emprunté de l’argent à un Juif avec intérêt et s’est converti, dans l’un ou l’autre cas, c’est-à-dire quel que soit le moment où le prêteur a réuni les intérêts et le principal en une seule dette, le prêteur juif peut recouvrer le principal et aussi les intérêts. Rava dit que Rav Ḥisda dit que Rav Houna dit : La halakha est conforme à l’opinion de Rabbi Yossei. Rava dit : Quelle est la raison de l’opinion de Rabbi Yossei ? Pourquoi est-il justifié de percevoir des intérêts auprès d’un Juif ? C’est afin que les gens ne disent pas : « Cet homme s’est converti par crainte pour son argent. » Les gens soupçonneraient qu’il s’est converti pour éviter de payer les intérêts.
§ Les Sages ont enseigné : Dans le cas d’un acte de prêt où sont consignés les détails d’un prêt avec intérêt, nous sanctionnons le prêteur ; par conséquent, il ne peut recouvrer ni le principal ni les intérêts. Telle est l’opinion de Rabbi Meïr. Les Sages disent : Il peut recouvrer le principal, mais pas les intérêts. La Guemara demande : Sur quel principe sont-ils en désaccord ? La Guemara explique : Rabbi Meïr estime que nous le sanctionnons en lui refusant ce qui est permis à cause de ce qui est interdit, tandis que les Sages estiment que nous ne le sanctionnons pas en lui refusant ce qui est permis à cause de ce qui est interdit.
Nous avons appris dans une Michna ailleurs (Shevi’it 10:5) : Les actes de prêt antidatés, dans lesquels la date inscrite sur le document est antérieure à celle à laquelle le prêt a réellement été accordé, ne sont pas valides, tandis que les actes de prêt postdatés sont valides. La Guemara demande : Pourquoi les actes antidatés ne sont-ils pas valides ? Certes, on ne peut pas s’en servir pour recouvrer la dette à partir de la première date, celle qui y est inscrite, car cela pourrait léser les personnes qui ont acheté des terres à l’emprunteur entre la date inscrite sur l’acte et le moment où le prêt a réellement été accordé. Les terres qu’elles ont achetées seraient alors grevées d’un privilège, alors qu’elles ne devraient pas l’être. Mais on devrait au moins pouvoir s’en servir pour recouvrer la dette à partir de la seconde date, celle à laquelle le prêt a réellement été accordé.
Rabbi Shimon ben Lakish dit : Cette Michna fait l’objet d’un désaccord et est enseignée conformément à l’opinion de Rabbi Meïr, qui a dit que le prêteur est sanctionné en lui refusant ce qui est permis à cause de ce qui est interdit. Ici aussi, puisqu’il a inscrit une date erronée, tout le document est invalidé à titre de sanction. Rabbi Yoḥanan dit : On peut même dire que cette halakha est conforme à l’opinion des Sages, car ici un décret rabbinique invalide le document, de peur que le prêteur ne recouvre la dette à partir de la première date. Si le document n’est pas invalidé, le prêteur s’y fiera et en viendra à recouvrer la dette selon la date qui y est inscrite.
La Guemara rapporte : Un homme avait donné son verger en garantie à un autre pour un prêt, et le prêteur en avait consommé les fruits pendant trois ans. Au bout de ce temps, le prêteur dit à l’emprunteur : « Si tu me vends le verger, tant mieux. Sinon, je cacherai l’acte d’hypothèque et je dirai : “Il a été acheté” », c’est-à-dire que je prétendrai l’avoir acheté et avoir perdu l’acte de vente. Puisque le champ est en ma possession depuis trois ans, je n’ai pas à fournir d’autre preuve, car selon la halakha, après trois ans d’exploitation d’un champ, celui qui l’exploite est présumé en être le propriétaire (voir Bava Batra 29b).
Lorsque l’emprunteur vit qu’il ne pouvait pas se protéger contre cette ruse, il conçut un stratagème : il alla transférer la propriété du champ à son fils mineur au moyen d’un acte de donation, puis vendit le champ au prêteur. Par la suite, il exigea l’annulation de la vente, au motif qu’au moment où il avait vendu le champ, celui-ci ne lui appartenait pas.
La Guemara précise la halakha : La vente n’était certainement pas valide, puisque le champ ne lui appartenait pas et qu’il ne pouvait donc pas le vendre. Mais la question est la suivante : Les dinars versés par l’acheteur sont-ils assimilables à un prêt consigné dans un acte de prêt, auquel cas l’acheteur peut recouvrer l’argent qu’il a payé même sur des biens vendus qui sont grevés d’un privilège ? Ou bien sont-ils assimilables à un prêt conclu par accord oral, auquel cas il ne peut pas recouvrer cet argent sur des biens vendus qui sont grevés d’un privilège ? Abayé dit : Cette question n’est-elle pas la même que celle de Rabbi Assi ? Car Rabbi Assi dit :
Texte source et traduction anglaise
בבא מציעא ע״ב א · texte araméen et hébreu
אִית לֵיהּ זְכִיָּה מִדְּרַבָּנַן. הָכָא נָמֵי לָא שְׁנָא.
וְלָא הִיא: יִשְׂרָאֵל אָתֵי לִכְלַל שְׁלִיחוּת, נׇכְרִי לָא אָתֵי לִכְלַל שְׁלִיחוּת.
תָּנוּ רַבָּנַן: יִשְׂרָאֵל שֶׁלָּוָה מָעוֹת מִן הַנׇּכְרִי בְּרִבִּית, וּזְקָפָן עָלָיו בְּמִלְוֶה, וְנִתְגַּיֵּיר. אִם קוֹדֶם שֶׁנִּתְגַּיֵּיר זְקָפָן עָלָיו בְּמִלְוֶה – גּוֹבֶה אֶת הַקֶּרֶן וְגוֹבֶה אֶת הָרִבִּית. וְאִם לְאַחַר שֶׁנִּתְגַּיֵּיר זְקָפָן עָלָיו בְּמִלְוֶה – גּוֹבֶה אֶת הַקֶּרֶן וְאֵינוֹ גּוֹבֶה אֶת הָרִבִּית.
וְכֵן נׇכְרִי שֶׁלָּוָה מָעוֹת מִיִּשְׂרָאֵל בְּרִבִּית וּזְקָפָן עָלָיו בְּמִלְוֶה וְנִתְגַּיֵּיר, אִם עַד שֶׁלֹּא נִתְגַּיֵּיר זְקָפָן עָלָיו בְּמִלְוֶה – גּוֹבֶה אֶת הַקֶּרֶן וְגוֹבֶה אֶת הָרִבִּית. אִם מִשֶּׁנִּתְגַּיֵּיר זְקָפָן עָלָיו בְּמִלְוֶה – גּוֹבֶה אֶת הַקֶּרֶן וְאֵינוֹ גּוֹבֶה אֶת הָרִבִּית.
רַבִּי יוֹסֵי אוֹמֵר: נׇכְרִי שֶׁלָּוָה מָעוֹת מִיִּשְׂרָאֵל בְּרִבִּית, בֵּין כָּךְ וּבֵין כָּךְ – גּוֹבֶה אֶת הַקֶּרֶן וְגוֹבֶה אֶת הָרִבִּית. אָמַר רָבָא אָמַר רַב חִסְדָּא אָמַר רַב הוּנָא: הֲלָכָה כְּרַבִּי יוֹסֵי. אָמַר רָבָא: מַאי טַעְמָא דְּרַבִּי יוֹסֵי – כְּדֵי שֶׁלֹּא יֹאמְרוּ בִּשְׁבִיל מְעוֹתָיו נִתְגַּיֵּיר זֶה.
תָּנוּ רַבָּנַן: שְׁטָר שֶׁכָּתוּב בּוֹ רִבִּית – קוֹנְסִין אוֹתוֹ, וְאֵינוֹ גּוֹבֶה לֹא אֶת הַקֶּרֶן וְלֹא אֶת הָרִבִּית, דִּבְרֵי רַבִּי מֵאִיר. וַחֲכָמִים אוֹמְרִים: גּוֹבֶה אֶת הַקֶּרֶן וְאֵינוֹ גּוֹבֶה אֶת הָרִבִּית. בְּמַאי קָמִיפַּלְגִי? רַבִּי מֵאִיר סָבַר: קָנְסִינַן הֶתֵּירָא מִשּׁוּם אִיסּוּרָא, וְרַבָּנַן סָבְרִי: לָא קָנְסִינַן הֶתֵּירָא מִשּׁוּם אִיסּוּרָא.
תְּנַן הָתָם: שְׁטָרֵי חוֹב הַמּוּקְדָּמִין – פְּסוּלִין, וְהַמְאוּחָרִין – כְּשֵׁרִין. מוּקְדָּמִין אַמַּאי פְּסוּלִין? נְהִי דְּלָא גְּבוֹ מִזְּמַן רִאשׁוֹן, נִיגְבּוֹ מִזְּמַן שֵׁנִי!
אָמַר רַבִּי שִׁמְעוֹן בֶּן לָקִישׁ: בְּמַחְלוֹקֶת שְׁנוּיָה, וְרַבִּי מֵאִיר הִיא. וְרַבִּי יוֹחָנָן אָמַר: אֲפִילּוּ תֵּימָא רַבָּנַן – גְּזֵירָה שֶׁמָּא יִגְבֶּה מִזְּמַן רִאשׁוֹן.
הָהוּא גַּבְרָא דְּמַשְׁכֵּין לֵיהּ פַּרְדֵּיסָא לְחַבְרֵיהּ, אַכְלַהּ תְּלָת שְׁנֵי. אֲמַר לֵיהּ: אִי מְזַבְּינַתְּ לַהּ נִיהֲלִי – מוּטָב, וְאִי לָא – כָּבֵישְׁנָא לַהּ לִשְׁטַר מַשְׁכַּנְתָּא וְאָמֵינָא: ״לְקוּחָה הִיא בְּיָדִי״.
אֲזַל קָם אַקְנְיַיהּ לִבְנוֹ קָטָן, וַהֲדַר זַבְּנַהּ נִיהֲלֵיהּ.
זְבִינֵי וַדַּאי לָא הָווּ זְבִינֵי. זוּזֵי כְּמִלְוֶה בִּשְׁטָר דָּמוּ וְגוֹבֶה מִנְּכָסִים מְשׁוּעְבָּדִים, אוֹ דִילְמָא כְּמִלְוֶה עַל פֶּה דָּמוּ וְאֵינוֹ גּוֹבֶה מִנְּכָסִים מְשׁוּעְבָּדִים? אָמַר אַבָּיֵי: וְלָאו הַיְינוּ דְּרַבִּי אַסִּי, דְּאָמַר רַבִּי אַסִּי:
Bava Metzia 72a · traduction anglaise de Sefaria
nevertheless, he has the power, by rabbinic law, to acquire an item by means of an act of acquisition performed by another? Here, also, it is not different; the Jew can perform an act of acquisition on behalf of the gentile even though there is no agency for gentiles.
The Gemara rejects this comparison: But that is not so. A minor Jew will eventually reach the stage of eligibility for agency, but a gentile will not reach eligibility for agency. Consequently, the Sages did not establish the power for gentiles to acquire an item by means of an act of acquisition performed by a Jew.
§ The Sages taught: In the case of a Jew who borrowed money with interest from a gentile, and the gentile lender established the interest as a loan for the Jewish borrower, i.e., he added the amount of interest to the principal and consolidated it into a single debt, and then the gentile converted, the halakha depends on the circumstances. If the gentile established it as a loan for him before he converted, he may collect the principal from the borrower and he may also collect the interest. Since it had already been consolidated into a single debt, it is as though he already collected the interest while he was still a gentile. But if he established it as a loan for him after he converted, he may collect the principal but may not collect the interest, as it still had the status of interest when he became a Jew.
And similarly, in the case of a gentile who borrowed money with interest from a Jew and the Jewish lender established the interest as a loan for the gentile borrower, and then the gentile borrower converted, if he established it as a loan before he converted, the Jew may collect the principal and may also collect the interest. If he established it as a loan for the gentile after he converted, he may collect the principal but may not collect the interest, as it still had the status of interest when he became a Jew.
The baraita continues: Rabbi Yosei says: If a gentile borrowed money with interest from a Jew and converted, whether in this circumstance or whether in that circumstance, i.e., regardless of when the lender consolidated the interest and principal into a single debt, the Jewish lender may collect the principal and he may also collect the interest. Rava says that Rav Ḥisda says that Rav Huna says: The halakha is in accordance with the opinion of Rabbi Yosei. Rava says: What is the reasoning behind the opinion of Rabbi Yosei? What is the justification for collecting interest from a Jew? It is in order that people will not say: This individual converted due to concern for his money. People will suspect that he converted in order to avoid paying the interest.
§ The Sages taught: In the case of a promissory note in which the details of a loan with interest were written, we penalize the lender, and therefore he may not collect the principal and may not collect the interest; this is the statement of Rabbi Meir. And the Rabbis say: He may collect the principal but he may not collect the interest. The Gemara asks: With regard to what principle do they disagree? The Gemara explains: Rabbi Meir holds: We penalize him with regard to that which is permitted due to that which is prohibited, and the Rabbis hold: We do not penalize him with regard to that which is permitted due to that which is prohibited.
We learned in a mishna elsewhere (Shevi’it 10:5): Antedated promissory notes, in which the date written in the document is earlier than the date the loan was actually transacted, are not valid, but postdated promissory notes are valid. The Gemara asks: Why are antedated documents not valid? Granted, they cannot be used to collect from the first date, the date written in them, because this could cause loss to people who purchased land from the borrower in the time between the date written on the promissory note and the time the loan was actually granted. The land they purchased would be subject to a lien when it fact it should not be. But at least they should be able to be used to collect from the second date, when the loan was actually granted.
Rabbi Shimon ben Lakish says: This mishna is subject to dispute, and it is taught in accordance with the opinion of Rabbi Meir, who said that the lender is penalized with regard to that which is permitted due to that which is prohibited. Here too, since he wrote an incorrect date, the entire document is invalidated as a penalty. And Rabbi Yoḥanan says: You may even say that this halakha is in accordance with the opinion of the Rabbis, as here there is a rabbinic decree invalidating the document lest he collect from the first date. If the document is not invalidated, the lender will depend on it and will come to collect repayment according to the date written on it.
The Gemara relates: There was a certain man who mortgaged his orchard to another as security for a loan, and the lender consumed the produce of the orchard for three years. At the end of this time the lender said to the borrower: If you sell me the orchard, that is good. But if not, I will hide the document of the mortgage and I will say: It is purchased, and that is why it is in my possession, meaning I will claim I purchased the field and lost the deed. Since the land has been in my possession for three years I do not have to bring any other proof, as the halakha is that after three years of use of a field there is a presumption of ownership for the one who uses it (see Bava Batra 29b).
When the borrower saw that he could not protect himself against the ruse, he devised a scheme: He went and transferred ownership of the field to his minor son by means of a deed of gift, and afterward sold the field to the lender. Subsequently, he demanded that the sale be annulled, since when he sold the field, it was not his.
The Gemara clarifies the halakha: The sale was certainly not a sale, since the field was not his to sell, but the question is: Are the dinars that the buyer paid similar to a loan with a promissory note, and therefore the buyer can collect the money he paid even from liened property that has been sold? Or perhaps it is similar to a loan by oral agreement, and therefore he cannot collect it from liened property that has been sold. Abaye said: Is this question not the same as that of Rabbi Asi? As Rabbi Asi says:
Texte de Sefaria : William Davidson Edition - Vocalized Aramaic (CC BY NC) ; William Davidson Edition - English (CC BY NC).
Scan de Baba Metsia 72a
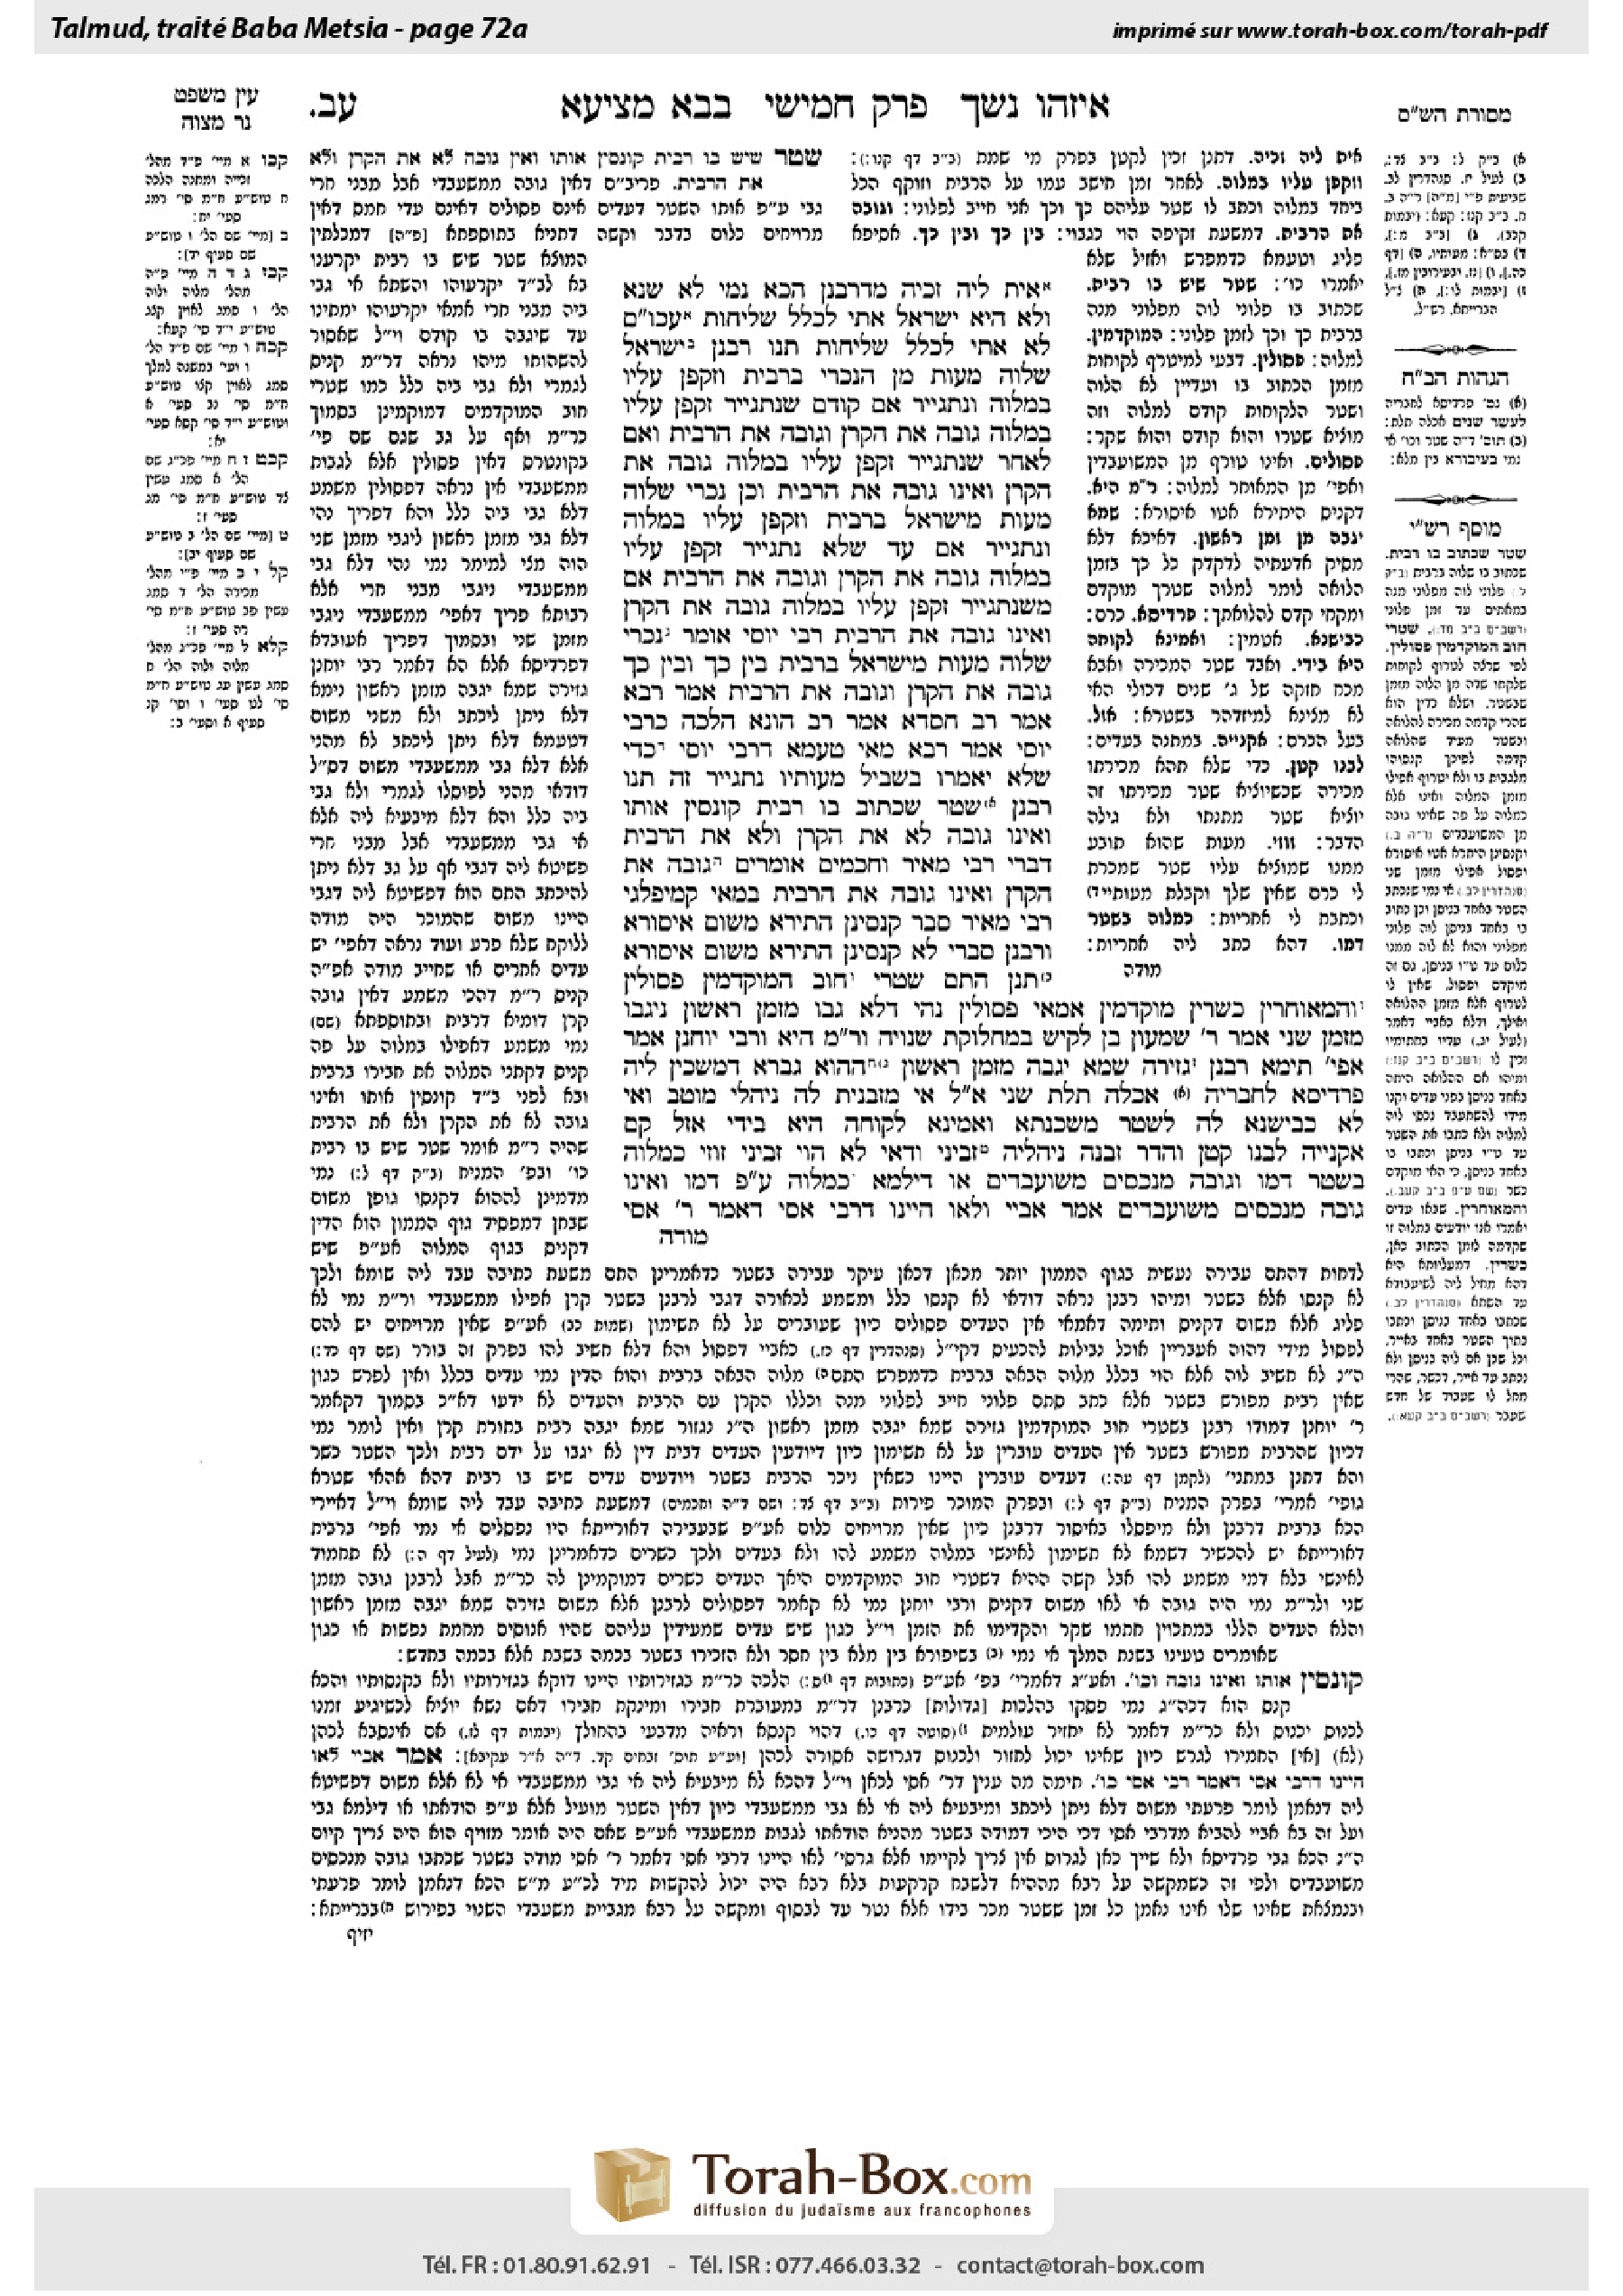
Scan : Torah-Box. Daf Study est un projet indépendant, sans affiliation ni approbation de Torah-Box ou de Sefaria.